

A mortgage may still be possible — even with bad credit
Missed payments, defaults, CCJs or other credit problems do not necessarily mean that you cannot get a mortgage. Our specialist advisers will review your complete circumstances and identify lenders whose criteria may be suitable for you.
Get your free mortgage assessment
Takes less than 30 seconds
We’ll only use your details to discuss your mortgage enquiry. No spam. No obligation.
FCA regulated
Access to 120+ lenders
Speak to an adviser now
Thousands of happy customers
HOW IT WORKS
A simple process from start to finish
1
Tell us your plans
Answer a few quick questions about your situation, budget and goals.
2
A specialist adviser calls
We’ll contact you to understand your needs and explain the options available.
3
We find the right options
Well research suitable mortgages and government schemes you may qualify for.
4
You take the next step
No obligation after your initial review. We’ll guide you through the next steps if you choose to proceed.
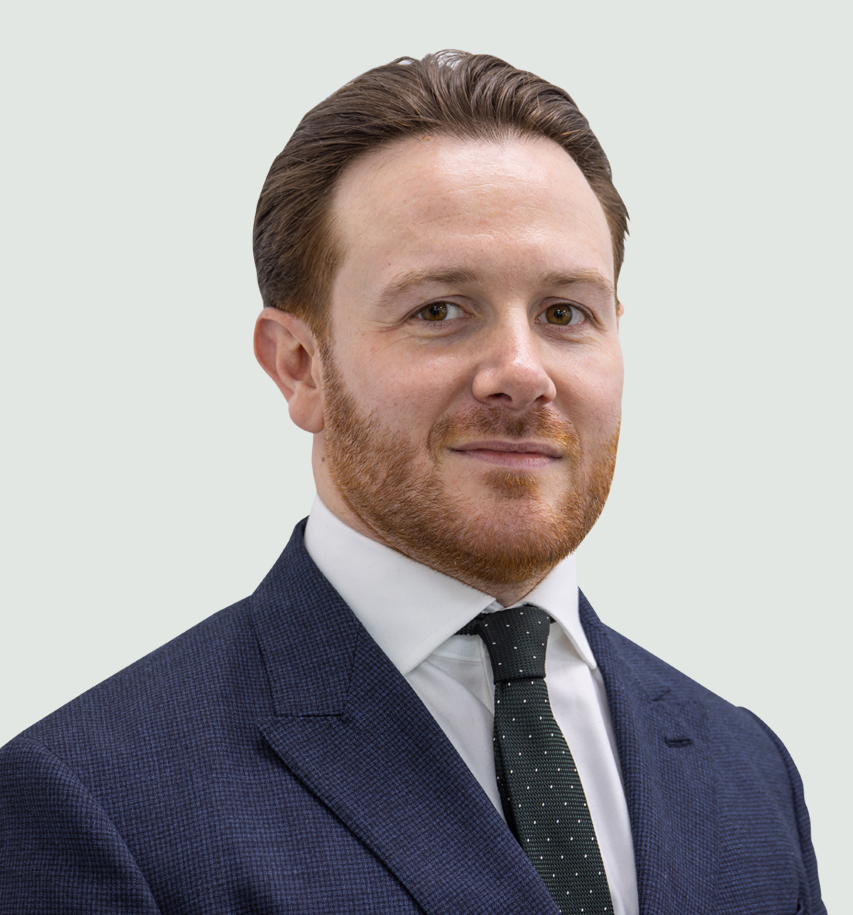
You'll be in safe hands
Hi, I’m Louis.
I’m a fully qualified mortgage adviser with 20+ years of experience helping borrowers just like you. I’ll be your dedicated adviser and I’m here to make your home-buying journey as smooth as possible.
Meet Our TeamLatest Testimonials
Real reviews from real customers.


Stamp Duty Calculator
View Our Top Lenders
Government and lender schemes you can use (2026)
Mortgage Guarantee Scheme — the permanent UK-wide scheme supports participating lenders in offering mortgages at 91% to 95% loan-to-value, which may allow eligible first-time buyers and home movers to purchase with a deposit as small as 5%. Availability, rates and lending criteria vary by lender.
First Homes — eligible first-time buyers in England may be able to purchase a qualifying new-build or resale First Home at a discount of 30% to 50% below market value. Household income limits and local eligibility rules apply, and some councils give priority to local residents, key workers or lower-income buyers.
Shared Ownership — buy a share of a home and pay rent to the housing provider on the remaining share. Initial shares are usually between 25% and 75%, although some properties are available from 10%. You may be able to purchase additional shares later through staircasing. Service charges and other costs may also apply.
Lifetime ISA — eligible savers can contribute up to £4,000 each tax year and receive a 25% government bonus of up to £1,000 a year. The funds can be used towards an eligible first-home purchase, subject to rules including account-opening, property price and withdrawal conditions.
Speak to an expert mortgage adviser from Trinity Finance
Our specialist mortgage brokers are here to guide you through the entire mortgage and finance process, helping you secure the best mortgage deal tailored to your needs.
Maria Goble
Mortgage Consultant
Louis Chalk
Mortgage Consultant
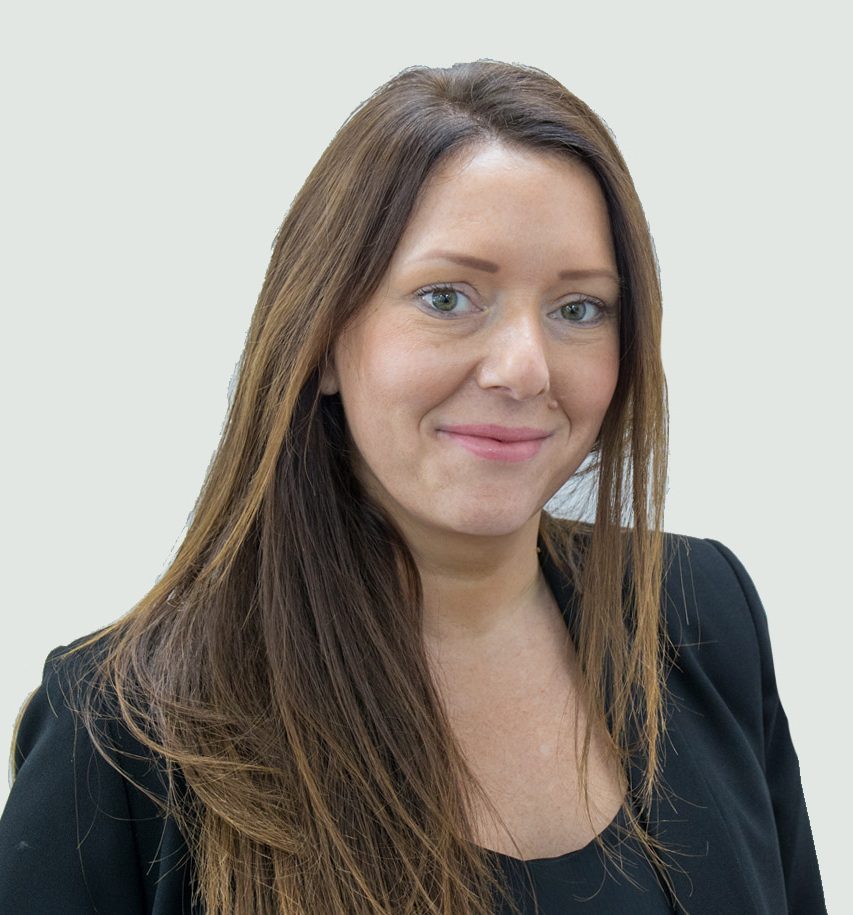
Emma Taylor
Mortgage Consultant
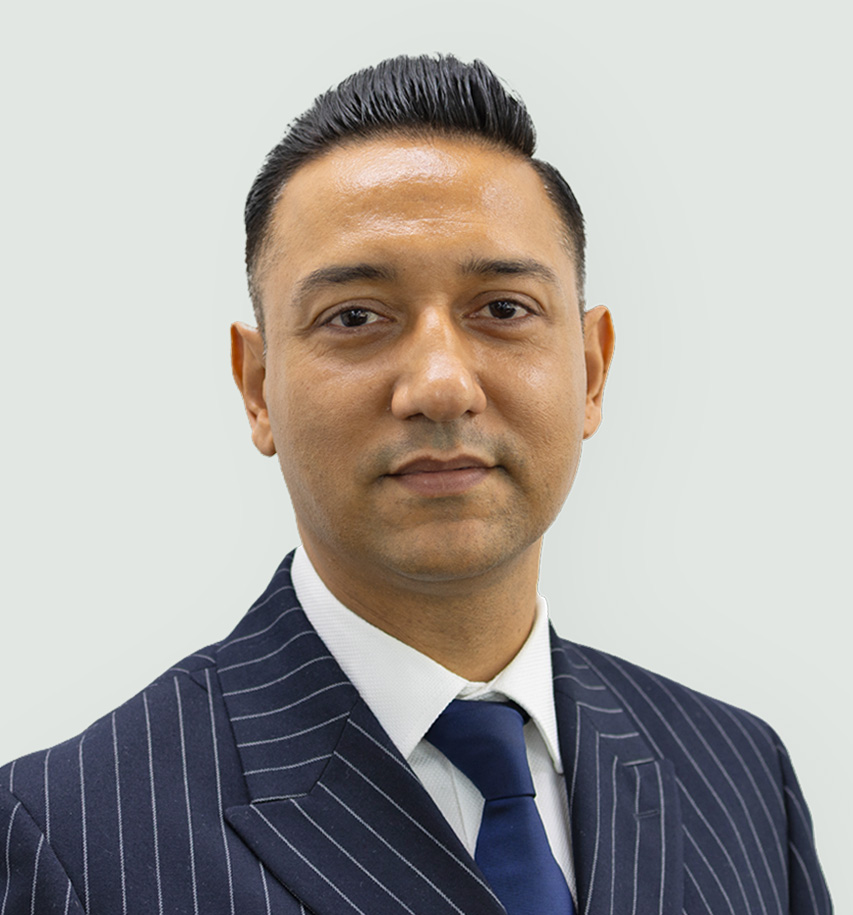
Vijay Mahajan
Mortgage Consultant
FAQs
It’s very unlikely that you’ll be approved for a 100% mortgage when you have bad credit. Lenders for poor credit applicants already take on increased risk and this increases further without a deposit. If you don’t have a deposit, ask your family members if they can help you out. They may be able to offer you a gifted deposit or agree to be a guarantor for you.
Yes, you can remortgage with bad credit. This is especially the case if you have minor credit issues, such as one late payment, or have a large amount of equity in your property. As remortgaging involves taking out a new deal with a new lender, you’ll need to pass their affordability checks. With regard to your credit history, they’ll need to know the reason for having bad credit and how long ago it occurred, how much of your current mortgage you’ve repaid and how well you’ve maintained your monthly mortgage payments. Just as you may need to use a specialist lender for a bad credit mortgage, you may need to use a specialist lender for a bad credit remortgage.
Lenders have different criteria and treat bad credit issues with varying degrees of flexibility. For example, an issue that occurred a few years ago and has now been resolved is favoured over a recent issue. Some lenders are more lenient when the reason for your bad credit resulted from an unforeseen life event, such as suffering from an illness or losing your job. In some cases, you may need to have a certain amount of equity in your property to satisfy the lender. Our mortgage brokers will ensure that your application is presented to the lender most suited to handling your case.
Bear in mind that you’ll have to pay a higher interest rate to be approved for a bad credit remortgage and the fees are also likely to be higher. This is because the lender is taking on more risk.
A lack of credit history means that you haven’t been able to develop a credit rating. For example, you may never have needed to use a loan or have never owned a credit card. Without a credit history or just having a low credit history, there’s nothing to show how you manage your finances. Therefore, lenders are unable to check your responsibility when it comes to making repayments. This can make it more difficult to be accepted for a mortgage but it is possible.
You may be required to pay a higher deposit and perhaps a higher interest rate to lower the lender’s risk. It’s recommended to start building a credit history as early as possible before applying for a mortgage as this can take time. Start by ensuring that you’re registered on the electoral roll. Then, apply for a credit builder card. This is a type of credit card that’s designed specifically to build your credit score when you have no or little credit history.
An adverse credit history, on the other hand, means that your credit report shows you’ve been unable to manage your finances successfully. The report may show that you’ve made late payments or missed them entirely. It may include serious credit issues, such as bankruptcy, and highlight multiple credit applications. These issues lower your credit score and show lenders that you’re unable to manage your finances sufficiently.
Our mortgage brokers can advise you on ways to improve your credit score before applying for a mortgage or remortgage.
Being approved for a mortgage if you’ve previously had a property that was repossessed can be difficult but it is possible. You’ll need to build your credit score back up to show lenders that you pay your bills on time. Having a larger deposit to put down will also help as this will reduce the lender’s risk. Our mortgage brokers will approach specific lenders who consider applications after a repossession. You will likely be charged a higher rate by the lender due to your adverse credit history.
Absolutely. As long as you make your mortgage repayments in full and on time each month, this will gradually increase your credit score. If you already have other lines of credit, such as a credit card, adding a mortgage is a good way to diversify your credit. This has a positive impact on your credit file as lenders can see that you’re able to effectively manage different types of credit.
Just be aware that when you first apply for a mortgage, there will be a temporary dip in your credit score. One reason for this is that lenders carry out a hard credit check on you to ascertain your creditworthiness. Another is that the new mortgage loan increases your overall debt, which affects the credit score calculations. As there’s no history on your credit file for paying off this large debt, a dip can be experienced until you make regular and on-time payments. Within a few months of making these payments, this minor decrease in your credit score should start to improve.
This is possible, depending on the severity and recency of the bad credit issue as well as the lender’s requirements. Not all lenders are willing to accept small deposits where bad credit is concerned. Those who do will only do so for minor credit issues that did not occur recently and will have strict lending criteria. If you can, save a bigger deposit before applying for a mortgage. Not only will this increase the number of lenders you can choose from but your application will be viewed more favourably. As such, you’ll benefit from a better interest rate than you would if paying a 5% deposit.
Before applying for a mortgage, there are a few things you can do to increase your chances of approval.
Increase your credit score
One is to improve your credit score, which lenders check when deciding whether to offer you a loan. There are numerous ways you can do this. For example, check that you’re on the electoral roll, pay your bills on time, reduce any outstanding debts as much as possible and check the accuracy of your credit report with each of the three main credit reference agencies and ensure that any mistakes are corrected. For the latter, make sure that any outdated financial connections are removed, such as one with an ex-partner. Also, reduce your spending where you can and cancel any unused subscriptions.
Increase your deposit size
Another is to save a bigger deposit. The more you can save, the less you’ll need to borrow and this lowers the lender’s risk. They’ll feel more comfortable about your commitment to making mortgage payments and will be more willing to approve your application. If you’re unable to save a deposit, ask a family member if they’ll consider giving you a gifted deposit to help you buy a property.
Consider your mortgage options
Before applying for a mortgage, consider the different types available rather than simply applying for a standard residential mortgage on your own.
For example, it can be beneficial to have a guarantor. This is usually a family member who is prepared to be responsible for your mortgage payments if you’re unable to make them. They need a strong credit rating and have to provide security for the lender. Despite being legally liable for the mortgage repayments, they won’t be named on the property deeds so you can enjoy sole ownership of your home.
Getting a joint mortgage is another option. If the other applicant has a strong credit rating, this can help to counteract your bad credit score. Both of your incomes will be taken into account when assessing your affordability and you can pool your savings for a bigger deposit.
A family offset mortgage is another possibility. With this type of mortgage, a family member links their savings account to your mortgage. The savings are offset against the mortgage balance and interest is only charged on the difference, improving your affordability. Your family member’s savings lower the risk for the lender, making them more likely to approve your mortgage loan when you have bad credit.
Having a bad credit rating tells lenders that you’re not good at managing your finances. Whether you’ve made late payments, missed payments or have defaulted on your payments altogether, this raises a red flag for lenders. A mortgage is a huge financial commitment and a lender needs to feel confident that you’ll repay the loan without any issues. Therefore, not all lenders are prepared to offer mortgages to borrowers with bad credit. This reduces the pool of lenders you can choose from and the subsequent range of deals offered to you.
Whilst it is harder to get a mortgage with bad credit, different lenders specialise in different aspects of adverse credit. As such, our mortgage brokers can ensure that your application is presented to the right one for your case to improve your chances of success. Specialist lenders take a more holistic approach to assessing applications compared with mainstream lenders. This means that they’ll look at your situation as a whole and assess your case on an individual basis.
Yes, although how long you need to wait after bankruptcy before being accepted for a mortgage varies between lenders. Most mainstream lenders only accept applications 6 years after your bankruptcy discharge, which typically occurs 12 months after the bankruptcy order. Specialist lenders can help much sooner than this, with more options becoming available the longer the period between your discharge and applying for a mortgage. You’ll need to pay a higher deposit and will more than likely have to pay a higher interest rate. The bankruptcy order will remain on your credit file for 6 years, regardless of when the discharge occurred.
When you have a bad credit rating, you’re considered a higher risk for lenders. To help mitigate this risk, they typically require you to pay a higher deposit. A higher deposit means that you’ll have a lower loan-to-value (LTV) ratio, which is the amount you need to borrow compared with the value of the property. This makes it easier for you to manage your mortgage payments as far as the lender is concerned.
The amount you need to pay as a deposit varies between lenders and the severity of your bad credit issue as well as how long ago it occurred. Typically, a large deposit of between 20% and 30% opens up more possibilities for you and increases your chances of approval. Specialist lenders may be willing to offer a higher LTV provided that you meet other requirements, such as having a guarantor for your mortgage. For minor credit issues, a smaller deposit, such as 10% or even 5% in some cases, may be accepted by lenders.
It’s possible to get a mortgage when you don’t have any credit history but it’s much more challenging. Lenders check your credit report to understand how well you manage your finances and this influences their lending decision. It may be that you’re a young borrower, have never needed credit before or have just moved to the UK, which is why you haven’t got a credit history. However, if you’ve never had a loan, credit card or any other type of credit account, there’s no record of how you maintain your payments. As such, there’s nothing for a lender to base their decision on.
Specialist lenders offer more flexibility with their lending criteria and assess applicants on a case-by-case basis. The amount of deposit you can pay, your income and how much you want to borrow will be considered. You may have to pay a higher deposit and/or a higher interest rate to be accepted. It’s recommended to start building your credit score well in advance of applying for a mortgage. Easy steps to take are registering on the electoral roll and applying for a credit builder card. The latter is a specialist credit card that’s designed to help you establish a credit history.
There isn’t a minimum credit score that applies to mortgage acceptance, although the higher your score, the better your chances of having a successful application. Lenders set their own credit score requirements, with some only accepting good or excellent scores and others offering a lot more flexibility by handling bad credit mortgages.
Lenders check your credit report with a credit reference agency but the one they use differs depending on their preferences. To complicate matters further, each of the three main credit reference agencies – Equifax, Experian and TransUnion – has its own scoring system. This means that a score can be considered good with one credit reference agency but the same score may be regarded as poor by another credit reference agency. For consistency and to get an overall view of your credit score across the three agencies, our mortgage brokers use Checkmyfile, which is a multi-agency credit report.
It’s important to bear in mind that other factors are taken into account by lenders, too, not just your credit score. They consider your income and expenses, employment status, deposit size, age, the property type and how much you want to borrow. If the rest of your application is strong, this can help if you have a low credit score.
Yes, it’s possible to take out a joint mortgage when your partner has bad credit. This is because lenders assess both of your creditworthiness and affordability for the mortgage. If you have a strong credit score, this can improve your chances of a successful application. Like any bad credit application, lenders will check the reason for the bad credit issue and how long ago it occurred. Just be aware that you won’t have such a wide range of lenders to choose from.
It will be helpful for your partner to try to improve their financial situation before you apply for a mortgage together. Lenders look more favourably on applicants who can show that they’re taking steps to do this.
Other aspects will also be taken into account for both applicants. This will include your incomes, employment statuses and outstanding debts. The more positive aspects there are, the more weight will be added to your application, increasing your chances of approval.
Any credit issues you’ve had will remain on your credit file for 6 years. This means that when lenders carry out a credit check on you, they can see your financial situation for this period. This is considered to be an adequate time frame within which to see how well you manage your finances.
Having bad credit doesn’t mean that you won’t be approved for a mortgage. We deal with specialist bad credit mortgage lenders and our mortgage brokers can ensure that your application is presented to the one most suited to handling your case.
Yes, as a first-time buyer with bad credit or a low credit rating, you can still be approved for a mortgage. You won’t have such a wide range of lenders to choose from as if you had a good credit rating but specialist lenders can help you buy your first home. They are able to take on more risk than mainstream lenders and offer more flexibility with their lending criteria. You may be required to pay a larger deposit or pay a higher interest rate.
Our mortgage brokers can ensure that your application is tailored and presented to the right lender. This avoids the risk of rejection, which would then show up on your credit file and be seen by other lenders.
Once approved for your first mortgage, it’s essential to make your monthly mortgage payments on time and in full. This will start to improve your credit score after just a few months. Just one late or missed payment, however, can damage your credit history even further, jeopardising any future loan applications. Our brokers will thoroughly assess your affordability first to make sure that you can comfortably afford the mortgage payments over your chosen term.
This really depends on how long you’ve been self-employed and how severe your bad credit is. If you have a long, successful track record of being self-employed and can provide the lender with certified accounts to prove this, then it will be easier to secure a mortgage when you have bad credit. If you’re newly self-employed, however, this increases the risk for the lender as you won’t have adequate proof of a regular income. This is on top of the risk that they’re already taking on with your bad credit status. This can make it harder to get a mortgage but it’s still possible.
Whilst your pool of lenders to choose from will be reduced, specialist lenders will be able to help you. They can take on higher levels of risk than mainstream lenders and offer more flexibility in their assessment criteria. Our mortgage brokers know which lenders have more flexible affordability criteria for self-employed borrowers and which ones specialise in different bad credit issues. This means that you can rest assured your mortgage application will be presented to the most suitable lender on your behalf.
Lenders check your credit report to understand how well you manage your finances. This determines their willingness to offer you a mortgage loan. The higher your credit score, the better your chances of being accepted for a loan. There are various steps you can take to improve your credit score over time and these include:
- Register on the electoral roll
- Pay your bills on time
- Stay out of your overdraft
- Reduce and, if possible, repay any outstanding loans
- Close any inactive accounts you have
- Check for and amend any mistakes on your credit reports
- Remove any old financial links on your credit reports, such as those with an ex-partner
- Avoid applying for lines of credit in the months before your mortgage application
Lenders vary in the credit reference agencies they use to check your credit history. The three main agencies are Equifax, Experian and TransUnion. Each of these records its data differently so you may find that your credit reports between each of these agencies vary slightly. Therefore, it’s worth checking each one for accuracy and ensuring that any amendments are made where necessary.
Each agency also has a different scoring system so your credit score may look vastly different between them. We recommend using Checkmyfile, which provides a multi-agency credit report. This pulls information from each of the three main credit reference agencies to give you a more accurate report and overview of your financial profile. It enables you to quickly identify and fix any discrepancies. You can also quickly pinpoint areas of your financial health that can be improved.
Having a good income can improve your chances of a successful application when applying for a mortgage with bad credit. The severity of the issue and how long ago it occurred will still be taken into account by the lender, though. Saving a bigger deposit will strengthen your application as will having a good track record of employment. It’s also best to improve your credit rating as much as possible before applying for a mortgage. Our mortgage brokers can ascertain the overall strength of your application and advise you on ways to improve it where possible.
A broker who specialises in bad credit mortgages is key to getting your application approved by a lender. They’ll assess your individual circumstances and advise you on ways to improve your chances of success before your application is submitted. Bad credit mortgage applications are typically complex and your broker will ensure that it is prepared correctly. They’ll advise you on the documentation that needs to be provided and will check your application for any mistakes.
Bad credit mortgage brokers know which lenders handle different bad credit issues and understand their varying eligibility criteria. Using their expertise, they’ll identify the lender best suited to your situation, whether they’re a mainstream or a specialist lender. Many specialist lenders are only available via brokers so you can rest assured that your application will be seen by the right one for your circumstances. This gives you a much greater chance of success than if you were trying to approach lenders yourself. Your mortgage broker will also negotiate for the best rate and terms on your behalf.
Once your application has been submitted, your broker will liaise with you and the lender throughout the mortgage process. This ensures that any queries are dealt with quickly and you benefit from as smooth and straightforward a transaction as possible.
Yes, this is possible, although you’ll have a smaller pool of lenders to choose from. When applying for a joint mortgage, each applicant’s affordability and creditworthiness are taken into account. The lender will assess the severity of the bad credit issue and how long ago it occurred. If the borrower without the bad credit issue has a strong credit rating and you both have good incomes and strong employment track records, this improves your chances of having a successful application.
It’s also better to clear any outstanding debts if you can and to increase your credit score as much as possible before applying. Despite one of you having bad credit, making a joint application can increase your borrowing potential so this is worth considering.
Bad Credit Mortgage Topics
Watch more videos from Trinity Finance
The Advantages Of Using A Mortgage Broker
Self-Build Mortgages With Trinity Finance
Copyright Trinity Finance Ltd 2026 ©
Trinity Financial Ltd Registered Company Number: 09621298 Registered in England and Wales. Registered Office; Trinity Financial Ltd, 72 – 74 Upper Wickham Lane, Welling, Kent DA16 3HQ. Trinity Finance is a trading name of Trinity Financial Ltd which is authorised and regulated by the Financial conduct Authority.