Mortgage advice built around how you really earn
Being self-employed should not prevent you from buying a home or finding a suitable mortgage. At Trinity Finance, we help sole traders, limited-company directors, partners, contractors and freelancers understand how different mortgage lenders may assess their income.
Get your free mortgage assessment
Takes less than 30 seconds
We’ll only use your details to discuss your mortgage enquiry. No spam. No obligation.
HOW IT WORKS
A simple process from start to finish
1
Tell us your plans
Answer a few quick questions about your situation, budget and goals.
2
A specialist adviser calls
We’ll contact you to understand your needs and explain the options available.
3
We find the right options
Well research suitable mortgages and government schemes you may qualify for.
4
You take the next step
No obligation after your initial review. We’ll guide you through the next steps if you choose to proceed.
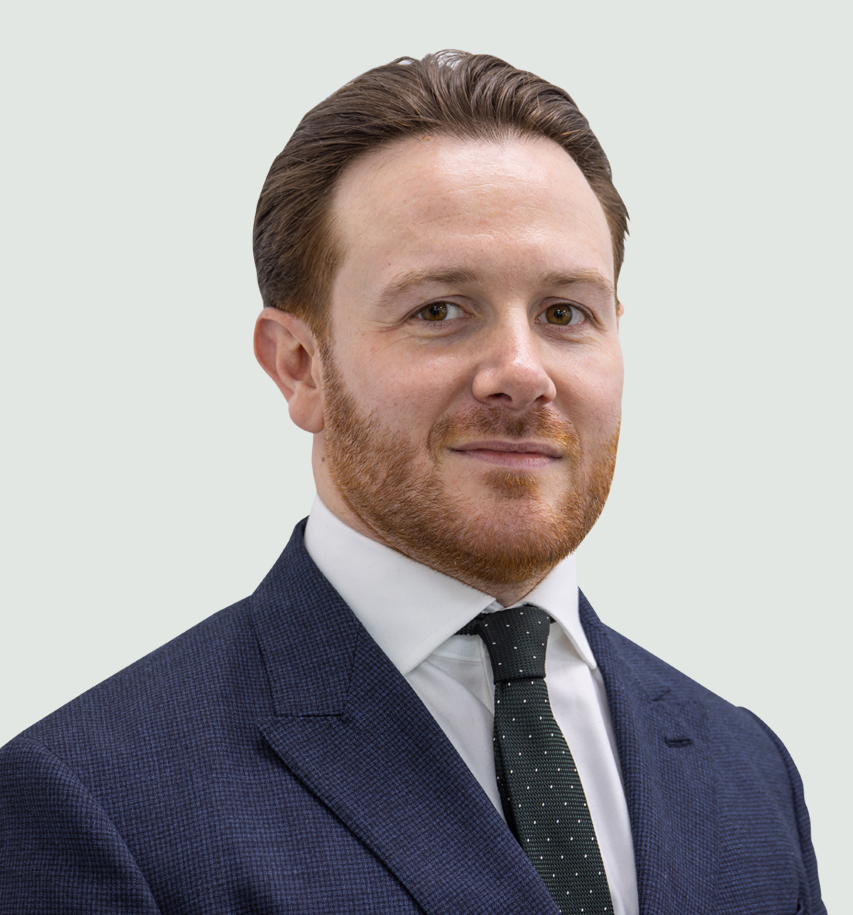
You'll be in safe hands
Hi, I’m Louis.
I’m a fully qualified mortgage adviser with 20+ years of experience helping borrowers just like you. I’ll be your dedicated adviser and I’m here to make your home-buying journey as smooth as possible.
Meet Our TeamLatest Testimonials
Real reviews from real customers.


 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
 Trustindex verifies that the original source of the review is Google.
Stamp Duty Calculator
View Our Top Lenders
Who we can help
Limited-company directors
Many company directors pay themselves through a combination of salary and dividends. However, this may not reflect the total strength or profitability of the business.
Depending on the lender and your percentage shareholding, it may be possible to consider:
- Director’s salary
- Dividend income
- Your share of company profit
- Retained profit within the business
- Other sustainable personal income
We will compare how suitable lenders assess limited-company income rather than relying on one standard calculation.
Sole traders
Lenders will usually assess a sole trader using net profit or taxable income rather than total turnover.
We will review your recent trading figures, tax calculations and any changes in profitability before checking which lenders may suit your circumstances.
Partners and LLP members
If you are a partner in a business or member of an LLP, lenders may assess your share of the partnership’s profits or your total remuneration.
The required evidence and calculation can vary according to the structure of the partnership and your ownership arrangement.
Contractors and freelancers
Contractors may be assessed using their accounts, tax calculations or, in certain circumstances, their current contract or day rate.
We will consider your contract history, remaining contract term, experience within your industry and the way you receive your income.
CIS subcontractors
Construction Industry Scheme income is treated differently between lenders. Some may assess you using your accounts, while others may be able to consider recent CIS statements or payment history.
Recently self-employed applicants
Having only one year’s completed accounts can reduce the number of available lenders, but it does not automatically prevent you from obtaining a mortgage.
Your previous employment, experience in the same industry, current business performance, deposit and recent bank statements may all help provide context.
Can we help with your situation?
- You only have one year’s accounts.
- You have recently moved from employment into self-employment.
- Your latest profit is higher or lower than the previous year.
- You retain profits within your limited company.
- You take a low salary and leave money within the business.
- You have multiple businesses or sources of income.
- Your income changes from month to month.
- You are a contractor working through a limited company.
- You have changed from a sole trader to a limited company.
- Your bank has declined your application.
- You have experienced credit problems.
- You need to remortgage after becoming self-employed.
A previous decline does not necessarily mean that every lender will reach the same decision. However, we will need to understand why the application was declined before recommending another approach.
You do not need a special type of mortgage
A “self-employed mortgage” is not a separate mortgage product. The main difference is how your income is evidenced and assessed.
Instead of relying on payslips alone, lenders may examine your accounts, tax calculations, tax-year overviews, business performance and bank statements. The information used will depend on how your business is structured and the lender you approach.
This is where selecting the right lender becomes important. One lender may base its assessment on a relatively conservative income figure, while another may take a broader view of the same business and accounts.
Our advisers will review your income before recommending a lender, helping you avoid applications to lenders whose criteria are unlikely to suit your circumstances.
Speak to an expert mortgage adviser from Trinity Finance
Our specialist mortgage brokers are here to guide you through the entire mortgage and finance process, helping you secure the best mortgage deal tailored to your needs.
Maria Goble
Mortgage Consultant
Louis Chalk
Mortgage Consultant
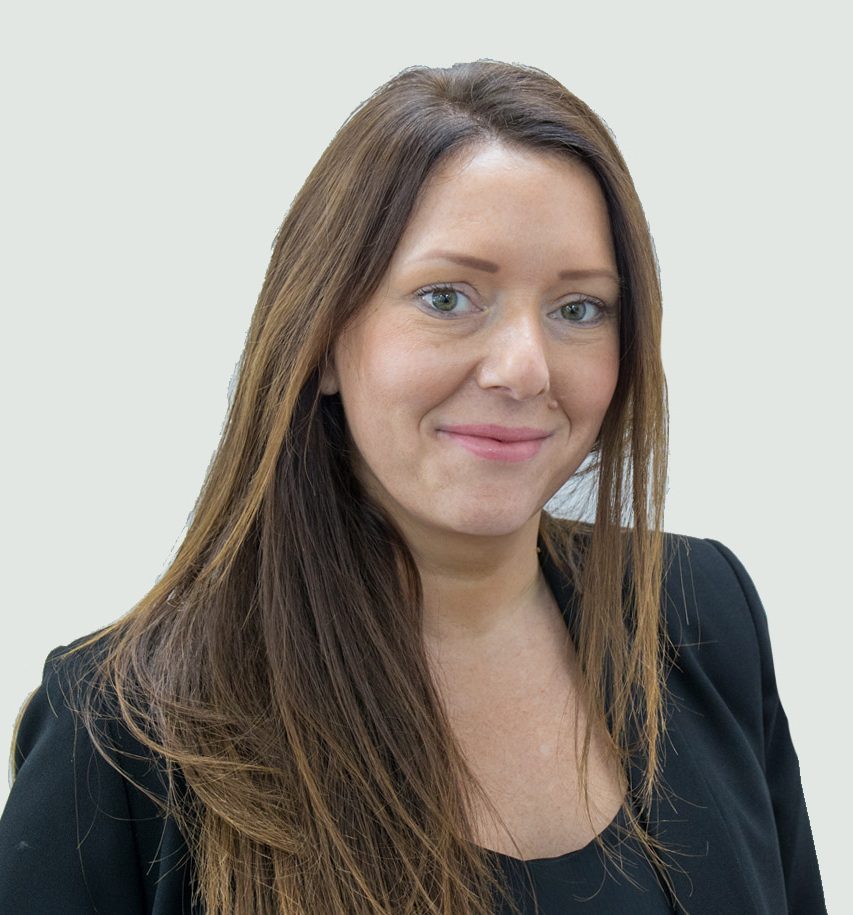
Emma Taylor
Mortgage Consultant
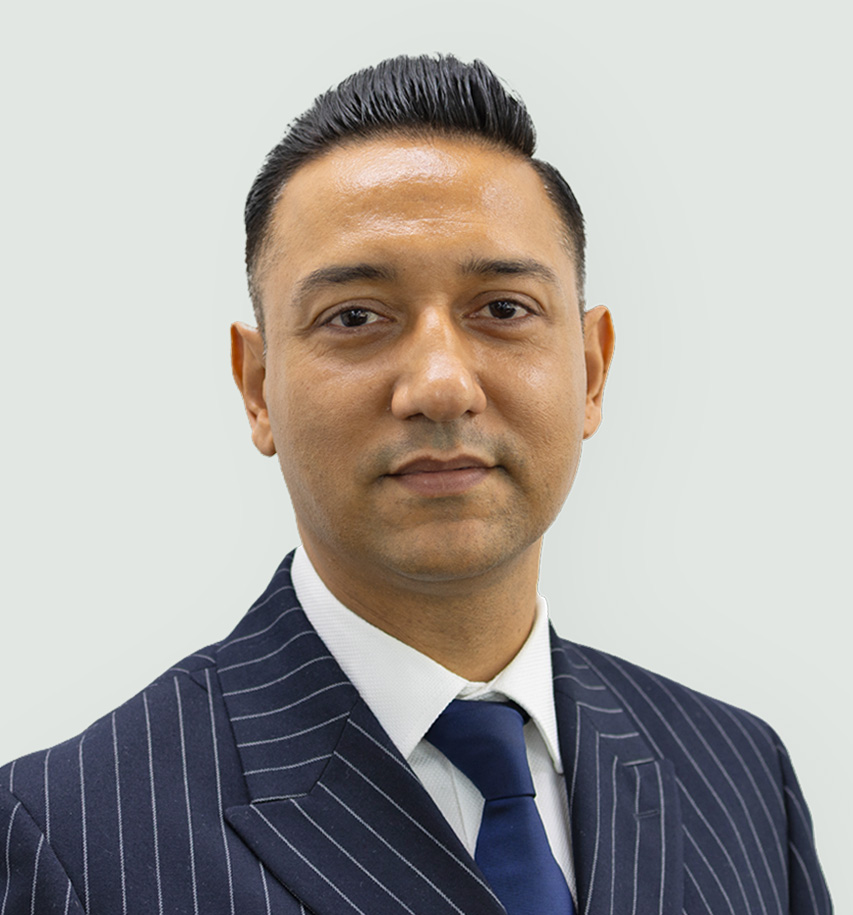
Vijay Mahajan
Mortgage Consultant
FAQs
Most lenders prefer you to have 2 to 3 years of accounts to show that you have a reliable income and can afford to make the mortgage payments. There are lenders, however, who will consider a self-employed application if you haven’t been trading that long. Specialist lenders can look at a year of accounts and some will even consider applications with no accounts.
There are several ways to improve your chances of being successful with your application in this case. It can be extremely helpful if your previous occupation was closely linked to the business you now operate. You’ll also need a sizeable deposit and a good credit score. When reviewing your application, specialist lenders can consider various other things, including:
- Payslips from your previous job
- A year-to-date overview of your income, prepared by a qualified accountant
- Future income projections
- Tax-deductible allowances within your overall earnings
- Allowances for losses in your accounts
- Salary and dividends received or the retained profits if you’re a company director
If you’ve recently switched from being a sole trader to a limited company, some lenders will insist on a year’s trading for the new entity. Others, however, won’t stipulate a minimum trading period as long as you can provide evidence of the income they require for your old entity or across the two entities.
Having accounts for a year or less can make it more challenging to secure a mortgage but not impossible. You’ll have a smaller pool of lenders who can help you and a limited range of mortgage deals as a result. You may also have to pay a higher interest rate to offset the lender’s risk. However, with enough evidence to satisfy a lender that you’ve got regular and ongoing work, you can still get a mortgage when you’re newly self-employed.
Generally, you don’t need to earn a certain amount to be accepted for a self-employed mortgage. There are some lenders, though, who do stipulate minimum income requirements for particular mortgage products or if they feel it’s necessary for your circumstances. For example, if you’re applying for a buy-to-let mortgage, they may wish to reduce the level of risk by ensuring that you earn a minimum annual income.
Yes, as long as you meet the lender’s requirements, you can get a mortgage as a first-time buyer when you’re self-employed. You need to prove your affordability for the monthly mortgage payments, have a good credit rating and a sufficient deposit.
Yes, it’s possible to get a mortgage when you’re self-employed and have a bad credit rating. Lenders have different criteria when it comes to offering mortgages with bad credit and our mortgage brokers will ensure that your application is presented to the right lender. We work closely with specialist lenders who offer more flexibility and assess applications on a case-by-case basis. They consider the type of credit issue, how it came about, the amount involved and when it occurred. These lenders usually accept debt management plans.
You may have to pay a higher interest rate and be offered a lower loan-to-value (LTV) ratio. This is to help mitigate the risk for the lender. However, once you start making regular mortgage payments, your credit rating will start to improve. There are ways to try and improve your rating before you apply for a mortgage, too, which our mortgage brokers can guide you on.
Being self-employed shouldn’t mean that you pay a higher mortgage rate than someone who is employed. You have access to the same mortgages and, therefore, the same interest rates. The rate you’re offered by a lender is based on other factors rather than your employment status, including how much you want to borrow, how much deposit you can pay and the length of mortgage term you prefer.
Therefore, as long as you have a good credit rating, an adequate deposit and can provide evidence to satisfy the lender that your income is reliable and can cover the mortgage payments, you should qualify for exactly the same rates as borrowers who are employed. The more deposit you have and the better your credit rating, the more deals become available to you and the more competitive the rates tend to be.
If your circumstances are complex and you need to use a specialist lender, however, then you may have to pay a higher rate. For example, if you’re newly self-employed or if you have a bad credit rating, a higher interest rate helps mitigate the risk for the lender.
If you’re struggling to meet the affordability criteria to buy a property on your own, a guarantor mortgage can be a good option. You may, for example, not earn enough to buy the property you want or the lender may offer you a lower loan amount to reduce their risk if your circumstances are complex.
With a guarantor mortgage, someone – usually a parent but they can be another relative or a close friend – signs a legal agreement confirming that they will cover your mortgage payments if you’re unable to. They also have to provide security for the lender, such as their property or savings. Your guarantor won’t be named on the property deeds so you can enjoy full ownership of your home.
Having a guarantor is beneficial in many ways. It can boost your affordability for a mortgage and the lender may be willing to accept a small deposit or even no deposit at all. Your guarantor must have a good credit rating, which is ideal if yours is low, you have bad credit or a lack of credit history. As your guarantor is taking on a lot of risk with this arrangement, they’ll need to take legal advice before proceeding.
No, agency workers and those who are paid via an umbrella company aren’t usually classed as being self-employed. As an agency worker, you’re placed with an employer via a recruitment agency. When you start working for that employer, they are responsible for your health and safety, just as they are for any employee. You also have a worker’s employment rights and, after 12 weeks in the same job, you have additional rights. These include equal pay to a permanent employee who is doing the same job, paid annual leave and automatic pension enrolment.
Despite having this employment status, you may still find it hard to get a mortgage. This is because lenders will be concerned with the stability of your income, just as they are for self-employed borrowers. Our mortgage brokers can help you with this. They can advise you on ways to maximise your borrowing potential and how to boost your chances of having a successful application. They can then tailor your application and present it to the lender most suited to dealing with your circumstances.
Yes, you can take advantage of buying a property via the shared ownership scheme if you’re self-employed. This government-backed scheme enables you to buy a share of a property – usually between 25% and 75% – and pay rent at a discounted rate for the remaining share. This solves any affordability issues with obtaining a mortgage as it’s based on the share of the property you buy rather than the full property value. It also makes it easier to afford the deposit. This needs to be a minimum of 5% of the value of your share of the property. You can increase your share of the property at a later date when you’re in a position to do so.
Just like you have access to the same types of mortgages as those who are employed, there are no differences in the deposit requirements just because you’re self-employed. Lenders vary with the deposits they’ll accept, depending on their lending criteria, the mortgage products they have available, the property you’re buying and your circumstances. As long as your business has a good track record and you earn an adequate, reliable income, you should be able to get a self-employed mortgage with a deposit of 5% to 10%.
However, as with any mortgage deal, the more deposit you can pay, the more deals will become available and the better the interest rates you’ll be offered. This is because paying a bigger deposit and borrowing a lower amount helps to mitigate the risk for the lender. As your self-employed income is likely to be irregular, it’s a good idea to save as much as you can to reduce the risk you pose in the eyes of the lender. Having access to more deals also increases your chances of finding a suitable self-employed mortgage.
As well as that, different loan-to-value (LTV) thresholds offer different rates, with better rates being offered the less you need to borrow. For example, if you can pay a 20% deposit, you’ll be offered a much better rate than for having a 10% deposit. If you manage to pay a 40% deposit, you’ll benefit from the lowest rates available. The lower your interest rate, the cheaper your monthly mortgage payments and the less you’ll have to pay overall during the mortgage term.
Get help with your deposit
If you’re struggling to save a deposit, our mortgage brokers can advise you on ways to help with this. For example, if a family member wishes to help, they can use their savings to offset your mortgage or offer to be your guarantor. They may be in a position to give you a gifted deposit. Or you may be able to take advantage of a government-backed low-deposit scheme.
As long as you meet the relevant lender’s criteria, you can get a buy-to-let mortgage when you’re self-employed. The affordability criteria for this type of mortgage usually focus on the anticipated rental income rather than your personal income. This typically has to cover at least 125% of the monthly mortgage payments, with some lenders insisting on 145%.
However, some lenders insist that you earn a minimum income, such as £25,000, and a minimum deposit of 25% is usually required. Lenders also tend to stipulate that you’re already a homeowner, whether you still have an outstanding mortgage or own your home outright. If you want to invest in a rental property, our mortgage brokers can match you with the right buy-to-let lender to suit your situation.
To prove your self-employed income, lenders usually require 2 to 3 years of certified accounts as well as SA302 forms for the last 2 or 3 years and/or a tax year overview from HMRC. You also need to provide business bank statements for the last 3 to 6 months and proof of your deposit.
If you’re a company director, you need to provide evidence of dividend payments or retained profits. If you’re a contractor, you need to provide evidence of your upcoming contracts. Depending on your circumstances, you may need to provide other documentation. This can include future income projections, evidence of additional earnings or details of any grants you’ve received.
Yes, lenders generally accept projected earnings and this is a good way to strengthen your mortgage application, especially if you haven’t been trading for very long. The projected earnings usually have to be certified by an accountant.
Yes, some lenders offer 95% mortgages to self-employed borrowers. You’ll need to prove your affordability for this and have a strong credit rating to be approved. With a high loan-to-value (LTV) ratio, you pose more of a risk to the lender so you’ll more than likely be charged a higher interest rate. This will make your monthly mortgage payments more expensive and will cost you more overall throughout your mortgage term. Our mortgage brokers know which lenders offer 95% mortgages and, having checked your affordability, will present your application to the most suitable lender.
It’s natural to include your business expenses on your tax returns to reduce how much tax you have to pay. However, when it comes to applying for a mortgage, this isn’t such a good idea. Doing so reduces your profit and the profit is what a lender looks at when calculating your affordability for a self-employed mortgage. Having less profit means that you won’t be offered as much for a mortgage loan. This can prevent you from buying the property you want. Therefore, in the lead-up to applying for a mortgage, try to limit the business expenses that you sign off.
When you’re newly self-employed, it can be more challenging to be accepted for a mortgage but it is possible. This is because lenders usually require 2 to 3 years of accounts to check your affordability. They need to be satisfied that your income is stable and they take an average of your earnings over that period to ensure that you can cover the mortgage payments. Specialist lenders can help, however, accepting a year of accounts and, in some cases, no accounts.
It will help your case considerably if your previous employment was linked to your new business. For example, if you were in the same line of work and especially if you will be contracting with the company you worked for. Specialist lenders usually accept payslips for your previous full-time employment. You’ll need to have a good credit rating and be able to pay a sizeable deposit.
No, self-certification mortgages no longer exist. They were once used by self-employed borrowers to self-certify how much they earned without having to provide the lender with any proof. This led to concerns that borrowers were taking on mortgages that they couldn’t actually afford. As a result, self-certification mortgages were banned by the Financial Conduct Authority.
There isn’t an actual ‘self-employed’ mortgage — when you’re self-employed, you have access to the same types of mortgages as those who are employed. The difference is in the way lenders assess your affordability for the loan amount that you’ve applied for. An employee is usually paid a set amount on a set day each month so the lender can check their payslips and see that they have a stable income. Your self-employed income is likely to fluctuate and come from multiple sources so the lender needs to carry out more thorough affordability checks. Instead of payslips, you’ll need to provide other documentation, such as certified accounts, SA302 tax forms and bank statements, depending on your circumstances and the lender’s criteria.
Watch more videos from Trinity Finance
The Advantages Of Using A Mortgage Broker
Self-Build Mortgages With Trinity Finance
Copyright Trinity Finance Ltd 2026 ©
Trinity Financial Ltd Registered Company Number: 09621298 Registered in England and Wales. Registered Office; Trinity Financial Ltd, 72 – 74 Upper Wickham Lane, Welling, Kent DA16 3HQ. Trinity Finance is a trading name of Trinity Financial Ltd which is authorised and regulated by the Financial conduct Authority.