

Specialist mortgage advice for landlords and property investors
Our specialist buy-to-let mortgage advisers can compare options from high-street banks and specialist lenders to find a mortgage suited to your property and investment plans.
Get your free mortgage assessment
Takes less than 30 seconds
We’ll only use your details to discuss your mortgage enquiry. No spam. No obligation.
HOW IT WORKS
A simple process from start to finish
1
Tell us your plans
Answer a few quick questions about your situation, budget and goals.
2
A specialist adviser calls
We’ll contact you to understand your needs and explain the options available.
3
We find the right options
Well research suitable mortgages and government schemes you may qualify for.
4
You take the next step
No obligation after your initial review. We’ll guide you through the next steps if you choose to proceed.
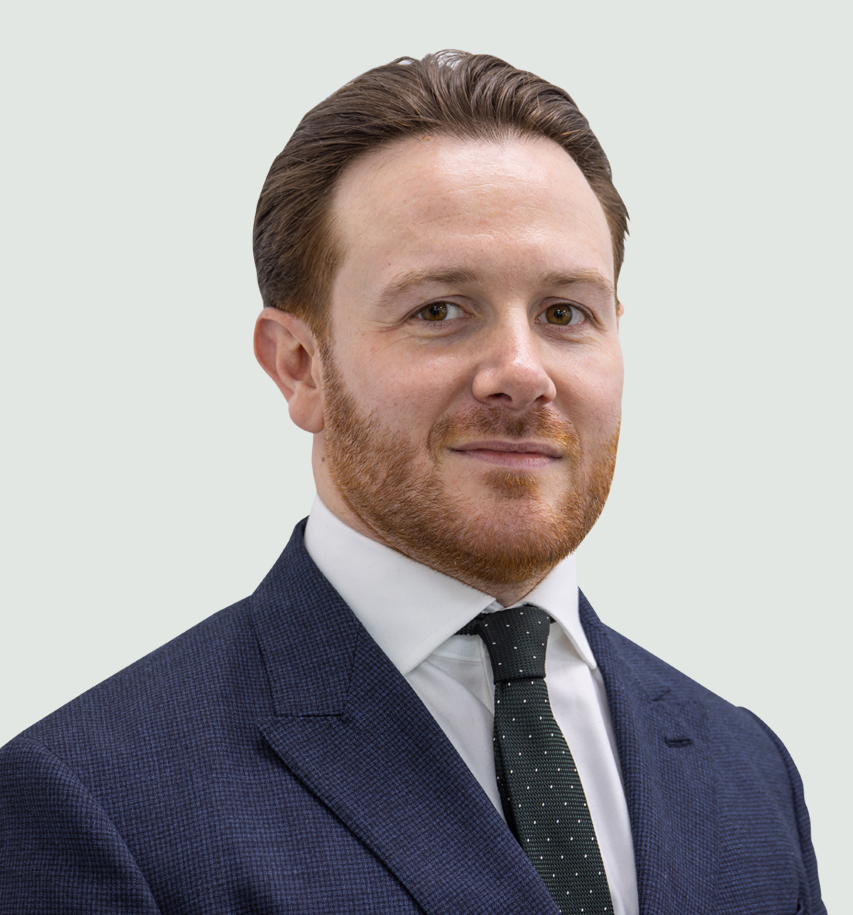
You'll be in safe hands
Hi, I’m Louis.
I’m a fully qualified mortgage adviser with 20+ years of experience helping borrowers just like you. I’ll be your dedicated adviser and I’m here to make your home-buying journey as smooth as possible.
Meet Our TeamLatest Testimonials
Real reviews from real customers.


Stamp Duty Calculator
View Our Top Lenders
How Can We Help?
Buying Your First Rental Property
Clear, step-by-step guidance for new landlords purchasing their first buy-to-let investment.
Expanding Your Property Portfolio
Mortgage options for experienced and portfolio landlords purchasing additional rental properties.
Buy-to-Let Remortgages
Review your current mortgage, secure a new deal or release equity for another property purchase, subject to lender criteria.
Limited-Company Buy-to-Let
Specialist mortgage options for landlords purchasing or refinancing property through a limited company or SPV.
HMO and Multi-Unit Mortgages
Access lenders that consider houses in multiple occupation, multi-unit freehold blocks and other specialist rental properties.
Complex Buy-to-Let Applications
Support for landlords with adverse credit, unusual properties, complex income or other circumstances that may not meet standard lender criteria.
Find the Right Buy-to-Let Mortgage for Your Property
Buy-to-let mortgage criteria can vary significantly between lenders.
The amount you can borrow may depend on the property’s expected rental income, your deposit, the property type, your experience as a landlord and whether you are purchasing personally or through a limited company.
Our advisers will assess your circumstances, explain your available options and manage your application from initial enquiry through to completion.
Speak to an expert mortgage adviser from Trinity Finance
Our specialist mortgage brokers are here to guide you through the entire mortgage and finance process, helping you secure the best mortgage deal tailored to your needs.
Maria Goble
Mortgage Consultant
Louis Chalk
Mortgage Consultant
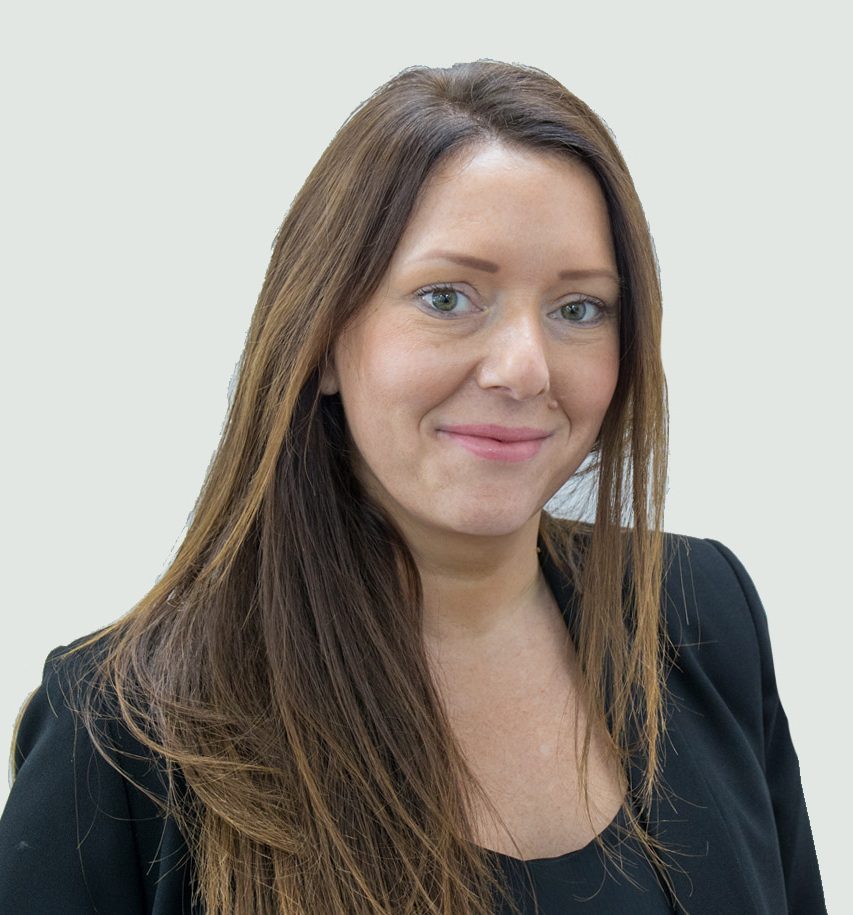
Emma Taylor
Mortgage Consultant
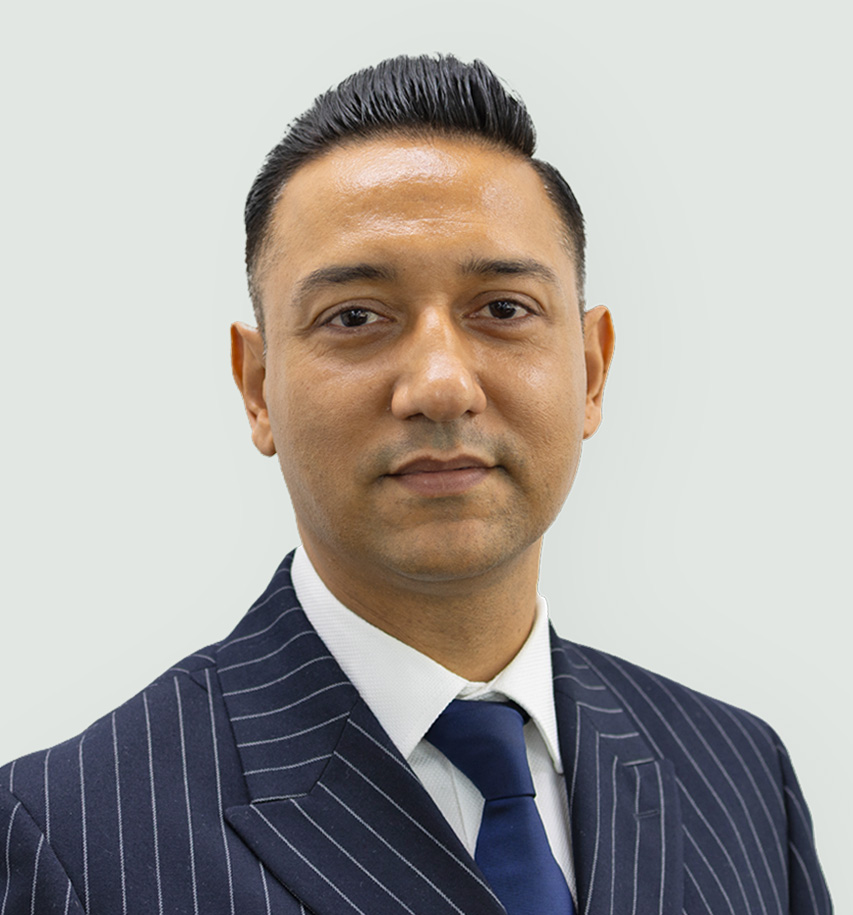
Vijay Mahajan
Mortgage Consultant
FAQs
Most buy-to-let mortgages are taken out on an interest-only basis. This means that you only pay the interest charged on the loan each month and don’t pay off any of the capital. At the end of the mortgage term, you have to repay the entire loan. As such, the lender will need to know your exit strategy. For example, whether you have savings, intend to sell the property, plan to sell another asset to cover the loan or prefer to refinance. Having an interest-only mortgage keeps your monthly payments lower, helping with your cash flow.
If you’d rather pay off the loan throughout the mortgage term, however, then a repayment mortgage is a better option. This option ensures that the loan is completely repaid by the end of the term so that you own the property outright. As the monthly payments are higher than those of an interest-only mortgage, you need to ensure that the rental income is high enough to cover them.
The terms for a residential mortgage are different from those of a buy-to-let mortgage. As such, if you rent out your home, you may be in breach of your mortgage terms. There can be serious consequences for this, such as being asked to repay your mortgage in full immediately. The exception to this is if you only need to rent out your home for a short time. In this case, you can ask your lender for their consent to let. If your lender agrees to this, be aware that your interest rate may increase. This is because renting out your home increases the level of risk.
Yes, as long as you meet the lender’s eligibility criteria, you can get a buy-to-let mortgage as a first-time buyer. It may be more challenging than buying a home for yourself and applying for a standard residential mortgage. This is because some lenders prefer you to already be a homeowner. Our mortgage brokers know which lenders offer buy-to-let mortgages to first-time buyers, so they can approach the right ones on your behalf.
Lenders vary in how many buy-to-let mortgages they allow you to have. Some may only allow one or two, whereas others may agree to multiple buy-to-let mortgages. Rather than limiting the number of buy-to-let mortgages you can take out with them, some lenders set a maximum borrowing limit across all of the products held with them. If you have several rental properties, you may prefer to finance them all using one portfolio mortgage.
All rental properties must have a valid Energy Performance Certificate (EPC). Your property must have a minimum energy efficiency rating of E before it can be rented out. If it doesn’t, you must ensure that the necessary work is carried out to bring the rating up to or above that level. Having a high energy efficiency rating for your property can be beneficial. Not only can this increase your property’s value but some lenders offer preferential rates for properties with a high rating.
Yes, you can get a buy-to-let remortgage just as you can remortgage when you have a standard residential mortgage. You may wish to do this because your deal is coming to an end and you want to get a better one. If you don’t remortgage, you’ll be moved onto your lender’s standard variable rate when the deal ends. This is usually higher than other rates so it will cost you more. Therefore, it’s advisable to remortgage before your deal ends. You can usually do this up to 6 months in advance.
Another reason you may want to remortgage is if you’ve built up some equity in your rental property. You may want to use it to carry out improvements or as a deposit to buy another property. Just be aware that if you remortgage before the tie-in period for your deal has ended, you may be penalised with an early repayment charge, which can be very costly.
Remortgaging can also be a good exit strategy if you don’t wish to sell your rental property at the end of the mortgage term.
A portfolio landlord is a landlord who owns four or more properties. Applying for a mortgage or remortgage as a portfolio landlord is slightly different from applying as a normal landlord. As you own multiple properties, you have to provide information on each of them. Some lenders place restrictions on portfolio lending, such as a maximum loan-to-value ratio across the entire portfolio or a maximum number of properties.
You may prefer to place all of your rental properties under one portfolio mortgage. This simplifies your finances as you only need to make one mortgage payment each month, check one statement and liaise with one lender. You can also do this with your property insurance, insuring all of your rental properties under one portfolio insurance policy. This is more cost-effective than taking out a separate landlord insurance policy for each property.
When financing your purchase with a buy-to-let mortgage, the lender will more than likely require you to have buildings insurance in place. It’s also recommended to take out contents insurance for any belongings you have left in the property for your tenants to use.
A landlord insurance policy can include both of these as well as additional types of cover that offer protection against the risks posed by rental properties. Typically, these include loss of rent insurance, property owners’ liability cover, rent income protection and replacement locks and keys. You can also choose from a host of optional add-ons, such as accidental and malicious damage, legal expenses, landlord home emergency cover, rent guarantee insurance, alternative accommodation, employers’ liability insurance, unoccupied property cover and more.
Buy-to-let refers to you buying a property with the sole purpose of renting it out to others. Let-to-buy, on the other hand, is when you rent out your current home so that you can buy somewhere else to live. This arrangement basically consists of two mortgages. You need to switch your current residential mortgage to a buy-to-let mortgage so that you can rent out your property. You also need to take out a residential mortgage for your new home. A let-to-buy arrangement is a niche product and our mortgage brokers work closely with lenders offering this financial solution.
If you wish to rent out your property to a family member, you need a specific type of buy-to-let mortgage, called a family buy-to-let mortgage. Unlike standard buy-to-let mortgages, this is a regulated mortgage. A family buy-to-let mortgage is hard to come by as few lenders are prepared to offer it. As our mortgage brokers have unrestricted access to first and second charge lenders, get in touch with us if you’re thinking about proceeding with this rental arrangement.
Lenders generally expect you to have a good credit score when applying for a buy-to-let mortgage. As such, there are some who won’t lend to you if you have bad credit. However, there are other lenders who will lend to you, assessing your case on individual merit. Your buy-to-let mortgage may take longer to arrange and you’ll have fewer options to choose from. You also need to bear in mind that you’ll be charged a higher interest rate and possibly higher fees. These are to compensate the lender for the higher risk involved with a bad credit buy-to-let mortgage. Our mortgage brokers can help you to navigate this type of issue when arranging a mortgage for your rental property.
A standard residential mortgage is designed for a home that you live in, whereas a buy-to-let mortgage is designed for a property that is rented out to others. Rental properties pose an increased risk for lenders so there are stricter terms as well as higher interest rates and fees to counteract this. You also need to pay a much higher deposit than for a standard residential mortgage.
Buy-to-let mortgages are also usually offered on an interest-only basis. This makes the monthly mortgage payments lower when compared with a repayment mortgage. However, the full loan must be repaid at the end of the mortgage term. This also means that the overall cost of the mortgage is higher as interest is always charged on the full loan amount rather than a reducing amount.
Yes, switching to a buy-to-let mortgage after taking out a bridging loan is a good exit strategy to use for that loan. For example, you may decide to use a bridging loan to buy a property at auction. Once the transaction has completed, you can repay the bridging loan by refinancing to a buy-to-let mortgage. Or you may wish to take out a bridging loan to carry out work on a property. When it’s finished and you’re ready to use the property as a rental investment, you can switch to long-term finance with a buy-to-let mortgage.
Buy-to-let means that your property’s use is specifically for renting out to tenants and receiving a rental income. A rental property carries more risk than an owner-occupied one. This is why you’ll be in breach of your mortgage if you rent out your home.
There may be an occasion, though, when you only want to rent out your home on a short-term basis. You may have to move away from home temporarily for work purposes, for example. This is where your lender’s consent to let comes in. A consent to let agreement is when your lender permits you to rent out your home, usually for up to a year, without changing your standard residential mortgage. As this arrangement increases the risk for the lender, they may charge you a higher interest rate and a fee.
No, as the owner of the buy-to-let property, you cannot live in it as this will breach the terms of the buy-to-let mortgage. If you’re found to be living in your buy-to-let property, the lender can demand that you immediately repay the mortgage in full.
Lenders have their own eligibility criteria but, generally, they do set a maximum age limit. This is the maximum age you can be at the end of the mortgage term. Usually, this is 75 or 80 years old.
Yes, if you prefer to invest in a buy-to-let property via a corporate setup instead of as an individual, you can do so using a limited company or a special purpose vehicle (SPV). You may wish to do this for tax purposes. The lending criteria are slightly different from applying as an individual because the lender needs information on the directors and shareholders. The interest rate is also usually higher for a limited company buy-to-let mortgage.
With a buy-to-let mortgage, the anticipated rental income is used in the affordability assessment to calculate how much you can borrow. The projected rental income must cover the mortgage payments by a specific ratio, which is usually 125%. This figure is known as the interest coverage ratio (ICR). For example, if your expected gross rental income is £750 per month, this covers monthly mortgage payments of £600. Many lenders stipulate a higher ICR of 145%.
Yes, you can remortgage your buy-to-let property just as you can remortgage your home. Remortgaging can be a good option if your buy-to-let deal is coming to an end and you want to secure a new deal to avoid paying your lender’s standard variable rate. Or you may have found a better deal with a cheaper interest rate and wish to remortgage to take advantage of it. Just bear in mind that you may be penalised with an early repayment charge if you remortgage too early. Another reason you may want to get a buy-to-let remortgage is to release some of the equity you’ve built up in the property to use as a deposit for a new property.
With an interest-only buy-to-let mortgage, you only pay off the interest each month. This means that at the end of the mortgage term, the entire loan needs to be repaid. As such, you need to plan how you intend to do this, which is known as your exit strategy.
You may decide to sell the property and repay the mortgage loan with the proceeds, for example. There is a risk here, though, that property prices might drop, leaving you with a shortfall that you have to find some other way to pay. It’s a good idea to save some of your rental income each month. That way, you can have peace of mind that you have a financial buffer for this purpose.
Rather than selling the property, you may wish to keep it as a rental investment. In this case, you can refinance to another buy-to-let mortgage deal.
Buy-to-let mortgages are designed for properties that are to be rented out on a long-term basis. When a property is to be used as a holiday home, the holiday lets are for short periods. As such, you need a specific holiday let mortgage. As seasonal rental incomes fluctuate for holiday homes, they pose a higher risk for lenders, resulting in stricter criteria. Whereas you can’t live in your own buy-to-let property, you can stay in your own holiday home. You just need to ensure that it’s available to holidaymakers for a certain amount of time during the year and that it is let out for a specific period.
Rental properties pose a higher risk to lenders than standard residential properties. This is due to potential void periods, late rental payments by tenants and fluctuating rental incomes for landlords. As such, lenders charge higher interest rates for buy-to-let mortgages to compensate them for this additional risk. Lenders also tend to charge higher fees for buy-to-let mortgages for the same reason.
Some lenders offer a bit more flexibility in their affordability assessments for buy-to-let mortgages. If your anticipated rental income isn’t adequate to cover the mortgage, your disposable income can be taken into account to cover the shortfall. This is known as top slicing.
Watch more videos from Trinity Finance
The Advantages Of Using A Mortgage Broker
Self-Build Mortgages With Trinity Finance
Copyright Trinity Finance Ltd 2026 ©
Trinity Financial Ltd Registered Company Number: 09621298 Registered in England and Wales. Registered Office; Trinity Financial Ltd, 72 – 74 Upper Wickham Lane, Welling, Kent DA16 3HQ. Trinity Finance is a trading name of Trinity Financial Ltd which is authorised and regulated by the Financial conduct Authority.
Your home may be repossessed if you do not keep up repayments on your mortgage.