

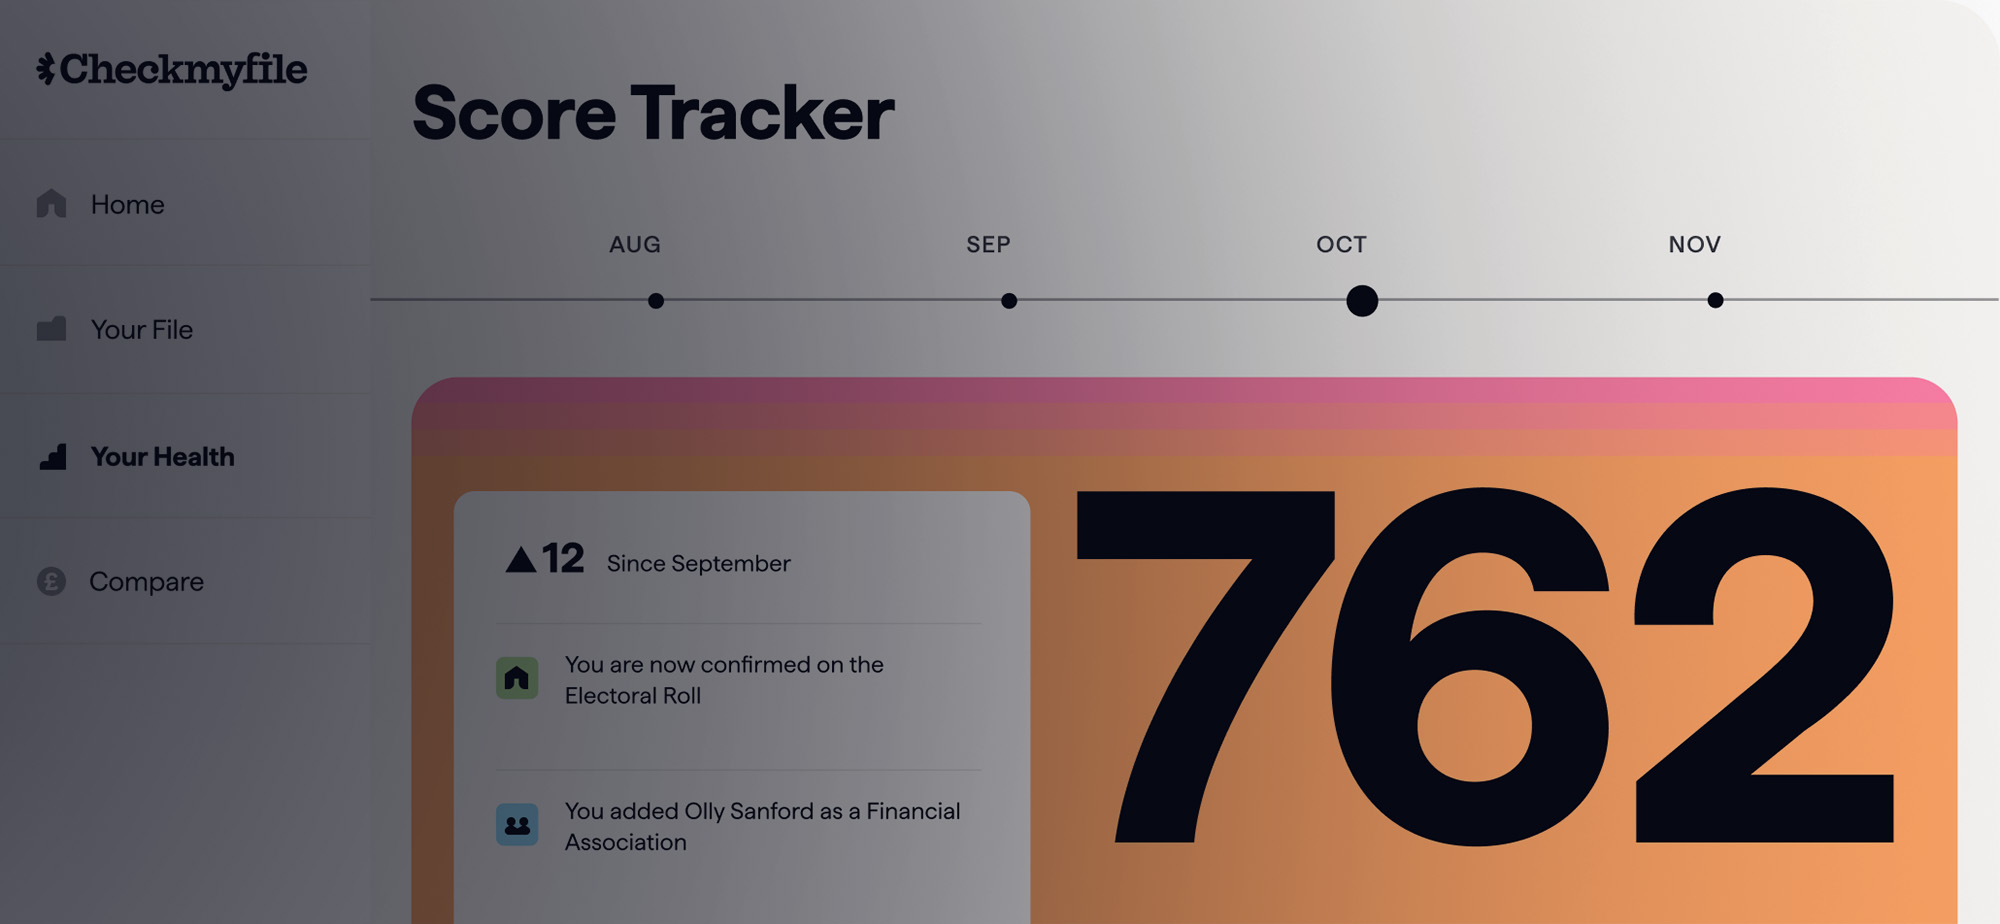
What is Checkmyfile?
When applying for a mortgage, the better your financial health, the better the outcome. Lenders need to check your creditworthiness before approving your application. They do this by checking your credit report. If this shows a low credit score, a lack of credit history or an adverse credit rating, it can affect your eligibility for a mortgage or the rates you are offered. It’s imperative, therefore, to check your credit report before applying for a mortgage. That way, you’ve got time to improve your credit rating where you can, increasing your chances of a successful outcome.
At Trinity Finance, we tackle any credit report issues head-on by requiring a full multi-agency credit report from Checkmyfile for each person on the mortgage application. This enables us to see what information lenders can view across the UK’s three main credit reference agencies. It helps us to spot and fix any issues before we submit your mortgage application. Doing so ensures that your mortgage application can progress efficiently by reducing unexpected delays and it also helps protect your credit file.
In this guide, we explain what Checkmyfile is, how it works, the information displayed on the credit report, the importance of using Checkmyfile and how it compares with other credit reference agencies.
Disclosure: This guide contains affiliate links, which means that we may earn a small commission at no extra cost to you if you click through and use the services.
Key points
- Checkmyfile provides a comprehensive multi-agency credit report in one place. It consolidates data from Experian, Equifax and TransUnion, giving you a clearer and more accurate overview of your credit history before applying for a mortgage.
- Reviewing your credit report early helps prevent delays and protects your application. By identifying inaccuracies, outdated information or credit issues in advance, you can resolve them before a lender carries out a hard search, improving your chances of approval.
- Using Checkmyfile does not affect your credit score. The service performs a soft search only, allowing you to monitor and improve your credit profile without leaving a visible footprint for lenders.
What is a credit score?
Before delving into Checkmyfile, we’ll explain what a credit score is and its significance when applying for a mortgage or remortgage. Your credit score is based on your financial behaviour, with your creditworthiness being given a numerical representation. This typically ranges from 0 to 1,000.
A higher credit score
A higher score is achieved by having good financial habits. For example, making repayments on time, ensuring that at least the minimum amount due is paid each time, refraining from maxing out any lines of credit and only applying for credit that you need. With a good credit score, lenders can see that you have a good history of borrowing and are less likely to default on your mortgage payments. This makes it easier to be approved for a mortgage. You may also be offered more competitive interest rates and better terms, such as more beneficial repayment terms and higher borrowing limits.
A lower credit score
A lower credit score, however, increases a lender’s risk as it shows a higher risk of defaulting on the mortgage. There are numerous reasons why you may have a low credit score, including a lack of borrowing history, making too many credit applications in a short period, making late payments, having mortgage arrears, a debt management plan being in place, having filed for bankruptcy, having CCJs or defaults registered against you and more.
With a low credit score, lack of credit history or bad credit, it can be much harder to be approved for a mortgage. A glance at your credit score enables lenders to determine your risk as a borrower, although other factors are considered too, such as your income, expenses and outstanding debts. Our expert brokers can guide you on ways to improve your credit score before applying for a mortgage. If you still have credit issues at that point, they can approach lenders who are better-equipped at dealing with an adverse credit history. The flexibility of these lenders when assessing your creditworthiness can significantly improve your chances of having a successful application.
How do credit scores work?
Your credit history information is taken from various sources by credit reference agencies and is collated in your credit file. These sources include the electoral roll, loan providers, banks, public records and debt collection agencies. There are three main UK credit reference agencies — Experian, Equifax and TransUnion. They look at the information in your file to generate a credit score. This is based on various factors, such as the types of credit accounts you have, the length of your credit history, your payment history and more.
Each credit reference agency assesses you in a slightly different way, which means that your credit score can vary between them. Their ranking categories for credit scores also differ. For example, a score assessed by one of them may be considered ‘good’ but the same score may be considered ‘excellent’ by another. To be more specific, Equifax uses a scoring system of 0 to 700, TransUnion from 0 to 710 and Experian from 0 to 999. This in itself makes it confusing to compare the scores shown on each credit report.
When checking your credit report, lenders can approach any of these credit reference agencies and it’s unlikely that you’ll know which one. This means that you need to try and keep your credit record held with each credit reference agency as up to date as possible.
Lenders also analyse your credit score differently, each having their own criteria and factoring in other aspects, such as your income and any outstanding debts you have. Therefore, it’s recommended to check your credit report regularly and improve your score wherever you can to optimise your position.
Why use Checkmyfile?
Checkmyfile provides you with more accurate results than the individual credit reports held by the UK’s three main credit reference agencies. This is especially the case as there can be discrepancies between them. For example, a missed payment may have been registered on your credit report for Experian but it may not have been recorded on your report for Equifax. As lenders favour different credit reference agencies, this can be worrying when it comes to the assessment of your creditworthiness. Checkmyfile, however, pulls details from Experian, Equifax and TransUnion. Therefore, you can be sure that all of the relevant information has been included, giving you a more accurate report.
If you see any incorrect information, you can amend it swiftly so that it doesn’t negatively impact your credit score. Checkmyfile shows you where there’s room for improvement with your credit score, enabling you to act on this straight away. With your detailed credit report at your fingertips, you can be proactive in managing your profile and improving your financial health. This gives you more confidence when applying for a mortgage and potentially opens up more opportunities with lenders.
The accuracy provided by Checkmyfile is essential from our point of view as mortgage brokers. Before submitting your mortgage application, we can get a clearer overview of your financial health and conduct a more accurate assessment. The comprehensive credit report enables us to spot any issues quickly and aim to resolve them before submission. For example, there may be name or address mismatches that need to be corrected or some of the data may be outdated, which needs to be resolved.
How does Checkmyfile work?
Every month, Checkmyfile updates your credit report by taking data from each of the UK’s three main credit reference agencies – Equifax, Experian and TransUnion. This compiled data provides you with a single, more comprehensive report, giving you access to a more accurate view of your financial profile and credit history. The report can include the following information:
- Credit accounts, such as loans, phone contracts, mortgages and credit cards
- Payment history, including on-time, late and missed payments
- Electoral roll registration
- Public records, such as county court judgements (CCJs), defaults, insolvencies and bankruptcies
- Financial associations and linked financial accounts. For example, you may have had an account with an ex-partner, which is still showing on your report.
As the three credit reference agencies each collect and report data differently, this single report makes it easy to identify any discrepancies and act on them. With instant access, you can also monitor it for any changes. This is a good way to detect signs of fraud or identity theft.
Calculating your credit score
Checkmyfile calculates a unique credit score based on the information received from each of the three credit reference agencies. The scoring system ranges from 0 to 999 and the higher your score, the better your credit health. The Checkmyfile score takes into account:
- The length of your credit history. A lack of credit history or none at all lowers your credit score.
- Your payment history. This tracks whether you make payments on time and includes payment information for up to the last 6 years. Any late or missed payments negatively affect your credit score.
- The types of credit accounts you have. These can include credit cards, phone contracts, mortgages and other instalment loans, payday loans and more.
- Your credit utilisation. This focuses on how much you are using of your available credit. Too much indicates that you may be under financial strain. Using more than 30% can negatively affect your credit score.
- Any recent credit applications you’ve made. Making too many credit applications in a short period can lower your credit score. It signifies that you’re unable to manage your finances well.
- Information from public records. This can include details of defaults, insolvencies, bankruptcies and CCJs. Any of these can negatively affect your credit score.
How do you sign up for Checkmyfile?
It’s quick and easy to set up a Checkmyfile account and access your credit report.
- Open an account: Click here to visit the website, then click on the ‘Sign up’ button. Enter your email address and a password, then tick the box underneath to confirm that you accept the terms of use and privacy policy. Click ‘Continue’ to begin your 7-day free trial. (When the free trial expires, it costs £14.99 per month and you can cancel at any time.)
- Enter your personal details: These include your full name, date of birth, current address, address history and payment information. The latter is for verification purposes and to enable a smooth transition when becoming a subscriber once the Checkmyfile free trial has ended. No payment will be taken during the free trial period.
- Verify your identity: You’ll need to answer some on-screen security questions to confirm your identity.
- View your credit report: Once the verification process has been completed, you’ll be able to access and view your credit report. You can also download a copy if you want to.
Review and correct your credit information
Once you’ve accessed your credit report, check the information carefully to ensure that there are no errors. This includes your payment history, current credit accounts you hold, financial associations and public records, such as CCJs and debt relief orders. If there are any errors, Checkmyfile can guide you on how to amend them.
Checkmyfile also details how each aspect of your report affects your credit score. It identifies actions that you can take to begin increasing your score. Once this has happened, it continues to guide you on how to maintain a higher credit score.
When you start monitoring your credit report regularly and notice any changes that occur, this will help you make more informed financial decisions.
How do you send someone your Checkmyfile credit report?
If you wish to send someone a copy of your credit report, you can save it as a PDF. Follow the steps below, depending on whether you’re using a desktop PC, an iOS device or an Android device.
Desktop PC:
- Click ‘Print/save my file’, which you’ll see at the bottom of the Home page.
- Click ‘Print/Save’ and you’ll see the print options.
- Select ‘Save as PDF’ from the drop-down list.
- Click ‘Save’.
- Select where you want to save the PDF and click ‘Save’.
iOS device:
- Click ‘Print/save my file’, which you’ll see at the bottom of the Home page.
- Click on the share icon in your Internet browser.
- Click ‘Options’.
- Select ‘PDF’ from the list and then click ‘Done’.
- Click ‘Save to Files’ and then select where you want to save the PDF.
Android device:
- Click ‘Print/save my file’, which you’ll see at the bottom of the Home page.
- Click ‘Print/Save’ and you’ll see the print options.
- Select ‘Save as PDF’.
- Click the download PDF icon.
- Select where you want to save the PDF and click ‘Save’.
At Trinity Finance, we need a full multi-agency credit report from Checkmyfile for each person on the mortgage application. Therefore, for a joint application, we require a separate PDF for each applicant. This enables us to progress your mortgage application efficiently.
Latest Testimonials


Speak to an expert Mortgage adviser from Trinity Finance
Our specialist mortgage brokers are here to guide you through the entire mortgage and finance process, helping you secure the best mortgage deal tailored to your needs.
Louis Chalk
Associate Director
Emma Taylor
Mortgage Consultant
Omer Mehmet
Managing Director
FAQs
What is a good credit score on Checkmyfile?
Checkmyfile uses a scoring system of 0 to 999. The UK’s three main credit reference agencies each have different scoring systems. Rather than averaging your score across the three reports, Checkmyfile accounts for the rest of the information provided to calculate a unique credit score that gives an overview of your financial standing. This score represents your likelihood of defaulting, which gives you an idea of how a lender will view you when checking your creditworthiness. Checkmyfile’s scoring system is broken down into the following credit score bands:
| Checkmyfile credit score | Likelihood of defaulting |
| Up to 449 | 38% |
| 450–639: | 24% |
| 640–719: | 15% |
| 720–829: | 8% |
| 830–900: | 4% |
| Over 900: | 2% |
Having a higher score reflects that you have a better credit rating and makes it easier to be approved for a mortgage. The higher your score, the more likely you are to be offered a higher loan-to-value (LTV) ratio by a lender and benefit from a better interest rate.
However, it’s important to understand that a lower score doesn’t mean that you won’t be accepted for a mortgage. Lenders look at your credit score to help determine your reliability for repaying the mortgage loan. But they have their own criteria and also take other factors into account, such as your income, the amount of deposit you can pay, the security you can provide and any existing debts you have.
How often does Checkmyfile update?
Checkmyfile updates your credit report each month so, at that point, it will show the up-to-date information from each of the UK’s three main credit reference agencies. Lenders and banks generally update their information about you on a monthly basis, whether that’s for an overdraft facility, a credit card, a new account that’s been opened, a mortgage, a personal loan, a line of credit, etc. This information can include details of your balances, repayment times, credit limits and more. This means that any changes to your accounts will reflect quickly in your Checkmyfile credit report.
However, lenders update their information at different times and each credit reference agency updates its system at different times. Therefore, you may be expecting a change to appear on your Checkmyfile report that doesn’t actually show until the following month. As Checkmyfile gives you an overview of your financial standing with all three credit reference agencies, it still gives you the most comprehensive idea of what a lender can see when checking your creditworthiness.
What is a multi-agency credit report?
Checkmyfile gathers your data from the UK’s three main credit reference agencies – Equifax, TransUnion and Experian – and creates a single, multi-agency credit report. This enables you to see all of the information from each of the credit reference agencies in one place. When you’re preparing to apply for a mortgage, a multi-agency credit report can be an invaluable tool. You can quickly get to work improving your credit score, whether that’s correcting any inaccuracies, reducing some of your loans or closing unused credit accounts.
The three credit reference agencies all collect and record data in different ways. This means that the information displayed on each report can differ, including your credit score. It’s both hard and time-consuming to make comparisons between them. With a multi-agency credit report from Checkmyfile, you have a unique credit score, a more detailed report and it’s much easier to spot any discrepancies. The comprehensive report allows for easy monitoring of your credit rating and tracking of any credit improvements. It’s also a good way to spot unusual activity, which may point to potential identity theft issues.
Is Checkmyfile accurate?
Checkmyfile pulls your credit data from each of the three main credit reference agencies. Each of them differs in their collection and reporting of data so each of your individual reports will vary slightly. This can lead to a potentially inaccurate view of your creditworthiness if just one of them is checked by a lender when assessing you for a mortgage. Having them collated together in Checkmyfile gives a more balanced and accurate representation of your credit history. As Checkmyfile is updated monthly, you also have the most accurate credit report at the time it’s updated.
From our point of view as mortgage brokers, the comprehensive report provides a more strategic overview of your finances, enabling us to conduct a more accurate assessment before submitting your application. Any errors can be amended and other potential issues can be tackled immediately. That way, your credit health is optimised as much as possible, helping to gain a more favourable mortgage outcome.
How much does Checkmyfile cost?
When you sign up for Checkmyfile, you’ll get a free trial for 7 days. This is perfect when you’re applying for a mortgage as you can check your credit report and take any necessary action to improve it before your mortgage application is submitted. This ensures that your credit report is the best it can be at the point a lender carries out their check on you.
You may, for example, have a positive credit score but it’s borderline for some lenders. Your Checkmyfile credit report enables you to spot any inaccuracies easily and it highlights areas that can be improved. With just a few tweaks, you may be able to increase your credit score. Ways to do this can include having an old financial link with someone removed, closing unused credit accounts, reducing an outstanding debt or registering on the electoral roll. The better your credit score, the wider your choice of lenders, the easier it is to be approved for a mortgage and the better the interest rates you’re offered.
If you decide not to continue using Checkmyfile at that point, you can cancel it before your free trial ends so that you’re not charged a subscription fee. Should you wish to keep using it, however, you’ll be charged £14.99 per month. As your credit report is ever-evolving, this can be well worth doing. You can track how your credit score changes over time and this can help you shape your financial habits using informed decisions. If you later decide you no longer wish to use Checkmyfile any more, you can cancel your subscription at any time.
Is my credit score on Checkmyfile the same as on other credit reference agencies?
No, each credit reference agency uses its own scoring system. This can make it hard to compare your credit reports from the three main credit reference agencies: Experian, Equifax and TransUnion. Checkmyfile consolidates the data from these agencies into one multi-agency credit report. That way, you can see the information that lenders can view across all of your credit reports. This makes it much easier to spot any issues and fix them before your mortgage application is submitted to a lender.
A unique credit score is calculated by Checkmyfile based on the information pulled from the three main credit reference agencies. It takes into account various factors, such as:
- The length of your credit history
- Your payment history
- The types of credit accounts you have
- Your credit utilisation
- Recent credit applications
- Information from public records
Checkmyfile uses a scoring system that ranges from 0 to 999. The higher your credit score, the better your credit health and the more favourably a lender may view your mortgage application.
Is it worth paying the monthly fee for Checkmyfile?
You can register with Checkmyfile for a free 7-day trial, which gives you time to check your credit history and get a one-off credit report before applying for a mortgage. If you have a strong credit score and can’t see much room for improvement, then you can cancel your subscription.
However, if you want to work on improving your credit score and prefer to monitor your credit profile in the long term, you can pay the monthly subscription fee of £14.99. You can easily cancel your subscription at any time but it can be worth paying to keep an active account for various reasons, as detailed below.
Why it’s worth paying for a subscription
- Your credit score changes over time and having access to Checkmyfile enables you to monitor these changes. You can then take any necessary action to either maintain a good score or increase a low score.
- Checkmyfile enables you to see the information that lenders check when evaluating your mortgage application. You may spot incorrect information on your credit file that has negatively affected your credit score. This gives you a chance to get it amended and improve your score in the process before you reach the stage where a lender needs to check your profile.
- If you have a low or borderline credit score, there are simple steps you can take to start improving it. For example, cancel any subscriptions you no longer use, remove any financial links that are no longer relevant, start to reduce your debts to lower your debt-to-income ratio and pay your bills on time. Checkmyfile gives you tips on how to build your credit history. It gives you clear, actionable steps to take based on your profile so that your credit score gradually improves.
- Your creditworthiness is an important part of a lender’s approval process. You don’t want to risk being rejected for a mortgage or having to pay a higher interest rate simply because you’re unaware of how your financial responsibility is reflected in your credit report. By staying on top of your credit report and working to improve it before you apply for a mortgage, you stand to benefit from a wider pool of lenders and a better chance of approval.
How can I improve my credit score?
Improving your credit score can take time but it’s essential to build it as much as you can to improve your chances of having a successful mortgage application. A quick way to improve your credit score is to register on the electoral roll. Other ways to increase your credit score over time are detailed below.
Ways to improve your credit score
- Ensure that some of the household bills are in your name. Pay these in full and on time each month to help build your credit score.
- If you have a lack of credit history, a good way to start building it is to open a bank account and set up regular direct debits to pay the utility bills. Another way is to apply for a credit builder credit card. You can then use this to make small purchases and pay the credit card bill in full each month.
- Avoid applying for new lines of credit. With each application, the relevant lender will carry out a hard search on your credit file, which other lenders can see. Too many hard searches in a short time frame can lower your credit score and raise a red flag to any new lenders checking your profile.
- Manage your credit utilisation. Try to keep the percentage of available credit you have under 30%. If it’s higher than this, it can negatively affect your credit score and tell lenders that you rely on credit.
- Pay your bills on time and in full. If you make late payments or miss payments altogether, this negatively affects your credit score. Keeping up with your payments, however, helps to increase your credit score. It also shows lenders that you can manage your finances responsibly.
- Correct any inaccuracies on your credit report. Inaccurate information can be harmful to your credit score so ensure that any errors are dealt with as quickly as possible.
- Reduce your debts. Excessive debt can negatively affect your credit score. Pay off as much of your debt as you can. Doing so not only benefits your credit score but it lowers your income-to-debt ratio, which lenders pay attention to when assessing your affordability for a mortgage.
Is Checkmyfile the same as Experian?
No, Checkmyfile and Experian are not the same.
Experian is a single credit reference agency and one of the three main ones in the UK, along with Equifax and TransUnion. The financial data between these three agencies differs as they collect data from varying sources and each uses its own scoring system. This means that your credit report from Experian can be different from the reports you get from Equifax and TransUnion.
Checkmyfile, on the other hand, pulls data from all three of these credit reference agencies to compile a multi-agency credit report. This gives you a comprehensive overview of your credit profile. As such, you can identify any discrepancies easily and take action to correct them, while also seeing at a glance how you can work to improve your credit score.
What information does my Checkmyfile credit report include?
Your Checkmyfile credit report provides you with up to 6 years of credit history from Equifax, Experian and TransUnion. This is presented in a single, manageable format with a side-by-side view. It includes:
- Your personal information, including your current and previous address history
- Electoral roll registration
- Details of your credit accounts, such as phone contracts, credit cards, loans and mortgages
- Payment history, including on-time, late and missed payments
- Financial associations, such as links to other people via joint accounts or mortgages
- Public records, such as defaults, county court judgements (CCJs), bankruptcies and individual voluntary arrangements (IVAs)
- Searches, including soft and hard searches. Whilst you can see soft searches listed on your credit report, lenders cannot see them. Lenders can, however, see any hard searches that are listed.
- Fraud warnings. These provide evidence of suspicious activity on your accounts so that you can check for potential fraud.
- Notices. You can add a Notice of Correction to your credit report to give context to issues, such as late or missed payments. Checkmyfile doesn’t recommend this for most people, however, because it can slow down credit applications and draw attention to unfavourable details.
How do I cancel Checkmyfile?
You can cancel your Checkmyfile subscription at any time and there are a few different ways you can do this. One is to send an email to the customer service team at help@checkmyfile.com. Another is to send a secure message via your account, asking for your subscription to be cancelled. Alternatively, you can log in to your account on your mobile or desktop PC and cancel your subscription in the billing section. To do this:
- Click on your initials — these will be at the top-right of the page on your mobile or the bottom-left of the page on your desktop PC.
- Click on the ‘Billing’ tab.
- Click ‘Cancel’.
Follow the onscreen instructions and then you’ll receive confirmation of the cancellation via email and a secure message from Checkmyfile.
Do mortgage lenders use Checkmyfile?
Lenders refer to their preferred credit reference agencies – usually one or two – when running their checks on you to help them make a lending decision. These agencies all collect and record data in different ways so your credit reports will vary between them. Lenders take into account your credit score and credit history but also have their own criteria and generally use their own credit score system. As such, they use this rather than the credit scores provided by the agencies.
Lenders don’t use Checkmyfile to guide them on lending decisions but, as the platform collects your credit data from the three main credit reference agencies, it gives you a comprehensive overview of what lenders can see. It’s an essential tool, therefore, that allows you to review your report before applying for a mortgage. It gives you time to remove any inaccuracies and improve your credit score where you can. Changing just one aspect, such as closing an unused credit account, may just push you from being on the boundary of acceptance by a lender to being approved for a loan.
What is the highest score on Checkmyfile?
Checkmyfile collects your credit data from the UK’s three main credit reference agencies and produces a unique credit score. This can range between 0 and 999, with 0 being the lowest score and 999 being the highest. Checkmyfile bases this score on your likelihood of defaulting so that you can see how a lender will view your creditworthiness.
For example, if you have a credit score between 0 and 449, there’s a 38% likelihood of defaulting according to Checkmyfile’s metric. In this case, it can be more challenging to be approved for a mortgage as you present a higher level of risk to the lender. As such, Checkmyfile will recommend that you take steps to improve your credit score. Don’t be disheartened if you have a low score as there can be many reasons for this. Lenders also take other factors into account when assessing you. If you have bad credit, we deal with specialist lenders who offer more flexibility with their criteria for a mortgage.
At the other end of the scale, with a Checkmyfile score of over 900, there’s only a 2% likelihood of defaulting. This means that you should be approved for a mortgage, be offered a higher loan-to-value (LTV) ratio and benefit from a competitive interest rate.
How is my personal information used by Checkmyfile and is it safe?
Checkmyfile displays your personal information and financial data in a multi-agency report to give you a comprehensive overview of your credit health and financial standing. This information can include your name, address history, whether you’re registered on the electoral roll, details of financial associations, your payment and borrowing history over the last 6 years, public records, such as CCJs or bankruptcies, details of recent searches carried out on your credit report and fraud alerts.
Checkmyfile is registered and regulated in the UK and is safe to use. It follows strict protocols to ensure the privacy and safety of your information. It employs the use of secure servers, industry-standard encryption and two-factor authentication. Its regular credit monitoring service can also alert you to any unusual activity. For example, it may highlight an unexpected search, indicating that someone has used your name to apply for credit. Or it may show an unrecognised credit account, such as for a credit card, which you didn’t open. This information enables you to identify potential identity theft or other fraudulent activity and act on it quickly.
Does using Checkmyfile affect my credit score?
No, checking your credit report on Checkmyfile doesn’t have any impact on your credit score. This is because a soft search is used when you check your own credit report online. This type of search doesn’t affect your credit score and cannot be detected by lenders when they check your credit file.
A soft search is different from a hard search. When you make a new application for credit, such as for a credit card or a mortgage, the lender carries out a check on your credit profile that’s known as a hard search. This leaves a visible mark on your credit file that other lenders can see. It can cause a temporary dip in your credit score and typically remains on your credit file for 12 to 24 months.
If multiple hard searches are carried out within a short time frame, this signals a higher risk to lenders. It looks as though you’ve applied for different credit accounts to borrow more, which indicates that you may be struggling to manage your finances. That’s why it’s advisable not to apply for any new lines of credit in the run-up to applying for a mortgage.
As checking your own credit report uses a soft search without any impact, this is a good way to review the information displayed on your credit file. You can then use it to improve your credit score over time where you can.
How does Checkmyfile compare with other credit reference agencies?
Each of the three main credit reference agencies – Equifax, Experian and TransUnion – collects data from varying sources and has its own scoring system. They assess your data differently and have different ranking categories for credit scores.
Mortgage lenders use their preferred credit reference agency, not all three. This is frustrating if your score shows as ‘excellent’ with one agency but as ‘good’ with the one your lender uses. Or, for example, if your ‘good’ score with one agency is displayed as ‘borderline good’ with another. This is even more of a concern if you have a low credit score.
There can also be discrepancies between the accuracy of the agencies’ reports. For example, a missed payment may be displayed for an old bill on your Equifax report but this may not show at all on your Experian credit report. As you won’t know which credit reference agency the lender is going to check, this means having to check all three credit reports to ensure they all display the correct information about you. This can be very time-consuming.
A multi-agency report with Checkmyfile
Checkmyfile helps you navigate these issues. It compiles the data it pulls from all three of these credit reference agencies into a single, comprehensive report with a unique credit score. With all of your financial information in one place, you can easily spot errors and take steps to fix them. Checkmyfile also highlights areas where you can improve your credit score, guiding you on how to do this.
By being able to monitor your three credit reports in one place, you can get a clearer idea of what information a lender will see about you, regardless of which credit reference agency they use. Checkmyfile offers more accurate information and gives you the opportunity to optimise your credit profile as much as possible before a lender has to carry out its checks.
What should I check on my credit report?
It’s important to check for errors on your credit report. Even small ones can have an impact on your credit score or cause issues as far as lenders are concerned. For example, check that:
- Your personal details are correct. This includes the spelling of your maiden or married names, your date of birth and your addresses for the past 6 years. Be sure to check the addresses that you have listed for old accounts, too.
- Your voting status is correct. Confirm that you’re registered to vote at your current address.
- The necessary proof of identity has been provided. Lenders use this to verify who you are and where you live.
- Your payment history is correct. If late or missed payments are incorrectly shown, take steps to rectify these entries.
- Any financial associations are accurate. If a previous financial tie, such as with an ex-partner, is displayed that you no longer share, make sure it is removed.
- Current credit issues are correct. Verify the accuracy of any issues, such as IVAs or insolvency records.
- Old credit issues have been removed. Check that any CCJs or defaults that are older than 6 years are no longer displayed on your credit report.
- Active accounts are correct. Check that your current credit cards, loans and overdrafts are listed correctly.
- Non-active accounts are displayed as such. Make sure that any old or closed accounts show as ‘settled’ or ‘closed’ rather than active.
- Hard searches are genuine. Review any applications for credit to ensure that you actually made them. If there are any hard searches that you don’t recognise, this can signal identity fraud.
Any outdated information or errors that you spot and correct can positively affect your credit score.
When should I check Checkmyfile before applying for a mortgage?
Ideally, you should check your credit report on Checkmyfile 3 to 6 months before applying for a mortgage. This gives you time to fix any errors and build a clean payment history.
Mistakes on your file may take several weeks or even months to correct so these need to be tackled as early as possible. When checking your payment history, lenders prefer to see that you have at least 12 months of clean, on-time repayments. Checking your credit profile some months in advance of your application gives you a chance to improve your payment history if you haven’t got a clean track record for that length of time at that point.
During this time, avoid applying for new lines of credit as these will trigger hard searches, increase your monthly debt obligations and signal that you’re a financial risk. This can jeopardise your mortgage application as lenders may be more cautious about offering you a mortgage.
This time frame also gives you time to register on the electoral roll if you haven’t already or to update your current address if need be. Keeping an eye on your credit report in the months leading up to your mortgage application also ensures you’ll spot any fraudulent activity that would otherwise disrupt the final lender checks.
Is Checkmyfile the best credit reference agency?
The best credit reference agency depends on your individual needs. Checkmyfile is a multi-agency credit report provider rather than a single credit reference agency. However, it is widely regarded as offering the best service compared with individual credit reference agencies. It provides a comprehensive overview of your credit profile, generating a single report from the data taken from each of the three main credit reference agencies.
This gives you invaluable insights into the information lenders can see about you. You can quickly identify discrepancies between the three main agencies’ reports and ensure they are corrected. You can also follow Checkmyfile’s personal recommendations on how to improve your credit score over time. Once your credit score starts improving, Checkmyfile will help keep you on track to ensure your score keeps rising.
From our point of view, the accuracy provided by Checkmyfile is essential. It enables us to try and resolve any issues spotted in your comprehensive credit report before submitting your mortgage application to a lender. This reduces unexpected delays, helps protect your credit score and enables your mortgage application to progress efficiently.
What should I do if I find an error on my Checkmyfile report?
If you find any errors on your Checkmyfile report, get in touch with the relevant credit reference agency as quickly as possible.
If the same error is found on more than one of the credit reference agencies’ reports, be aware that each one operates a different dispute process. This means that only correcting a mistake on one agency’s credit report doesn’t mean that the mistake will be rectified on another’s. You’ll need to contact each one individually.
Allow adequate time for the errors to be rectified and the updates to be reflected on your report before submitting your mortgage application.
Not all discrepancies will necessarily affect a lender’s decision. Our mortgage brokers will go through your Checkmyfile report to help ascertain which issues need to be dealt with as a priority.
If you struggle to resolve the issues yourself, Checkmyfile offers a Data Dispute Resolution service. With this service, they can contact the relevant credit reference agencies on your behalf.
Contact Form
Mortgage Lenders
Partner with specialist lenders who understand finance


