

Expert Lifetime Mortgage & Home Reversion Advice from Trinity Finance
If you’re a homeowner aged 55 or over and looking to unlock tax-free cash from your property, equity release can be a smart solution — when guided by expert advice tailored to your circumstances. At Trinity Finance we specialise in helping the over-55s population release value from their homes with clarity, integrity and a fully regulated, whole-of-market approach.
Why Choose Equity Release?
Equity release offers you the opportunity to:
- Access tax-free cash while you continue to live in your home.
- Pay off an existing mortgage or other debts to reduce monthly commitments.
- Fund lifestyle goals such as home improvements, family support, or travel.
- Stay in your property for life (subject to lender terms) with options to move if needed.
- Benefit from the protections of the Equity Release Council such as the no-negative-equity guarantee.
Every case is unique — so the key is getting independent, whole-of-market advice to ensure equity release really is right for you.
How Much Can You Release?
The amount of cash you can unlock depends on:
- The value of your property.
- The age of the youngest homeowner.
- Any outstanding mortgage or secured loan to be repaid.
- The type of plan chosen (lifetime mortgage or home reversion) and the interest rate or reversion percentage.
For example, many plans allow you to borrow up to around 50-60% of the property value (for eligible applicants) under a lifetime mortgage.
We can provide a free no-obligation calculation for you to see how much you might release — call us or use our online form.
What Can You Use the Cash For?
The possibilities are wide-ranging — here are some popular uses:
- Clearing an existing mortgage to reduce monthly payments.
- Paying off other secured or unsecured debts for peace of mind.
- Carrying out home improvements (kitchen, bathroom, conservatory etc.).
- Helping family members financially (e.g., paying for grandchildren’s education or a deposit).
- Funding major life events (holidays, travel, weddings) or topping up retirement income.
- Buying a new car, or simply enjoying some extra financial freedom later in life.
How Does Equity Release Work?
The two main types
Lifetime Mortgage
- Borrow against your property’s value while living there, interest may roll up or you can make payments.
- The loan plus interest is typically repaid when you die or move into long-term care.
- Your estate will never owe more than the home’s value (no-negative-equity guarantee).
Home Reversion Plan
- You sell part or all of your home to a reversion provider in return for a lump sum or regular income, and retain the right to live there rent-free.
- On your death or move to long-term care the property is sold and the provider receives their share.
Eligibility and key factors
- Homeowner age: most lenders accept applications from age 55 upwards (and sometimes younger).
- Property value: typically there is a minimum value (often around £60,000-£70,000) and property type criteria (not all property types eligible).
- Outstanding mortgage/secured debt: if you still have a mortgage it must usually be repaid via the equity release funds or you will need to satisfy lender criteria.
- Health and lifestyle may affect how much you can borrow under a lifetime mortgage.
What to expect
- You receive an illustration showing the amount you could borrow, interest roll-up, and impact on your estate.
- Advice from a regulated adviser is a legal requirement — you cannot proceed without it.
- The value of your estate will reduce and may affect entitlement to means-tested benefits.
- You may still move house under the terms of your plan (subject to lender criteria).
Why Choose Trinity Finance?
Independent whole-of-market adviser
We don’t just offer one lender’s product — we search across all major providers to find the best fit for you.
Trusted experience
Our team specialises in later-life finance and understands the sensitivities around equity release.
Regulated and compliant
We are authorised and follow the standards required by the FCA and the Equity Release Council.
Transparent costs
Before you commit we’ll provide a clear breakdown of all fees, our service, and the lender terms.
Personalised service
We assign you a dedicated adviser, provide a bespoke recommendation document and guide you through the entire process from initial discussion to completion.
Support for your family and estate planning
We cover how the plan may affect your estate, inheritance and benefits — helping you make informed decisions.
Trinity Finance Office
Opening Hours
Monday: 9 am–5 pm
Tuesday: 9 am–5 pm
Wednesday: 9 am–5 pm
Thursday: 9 am–5 pm
Friday: 9 am–5 pm
Saturday/Sunday: Closed
Latest Testimonials


Speak to an expert Equity Release Mortgage adviser
Our specialist equity release mortgage brokers are here to guide you through the entire mortgage and finance process, helping you secure the best equity release mortgage deal tailored to your needs.
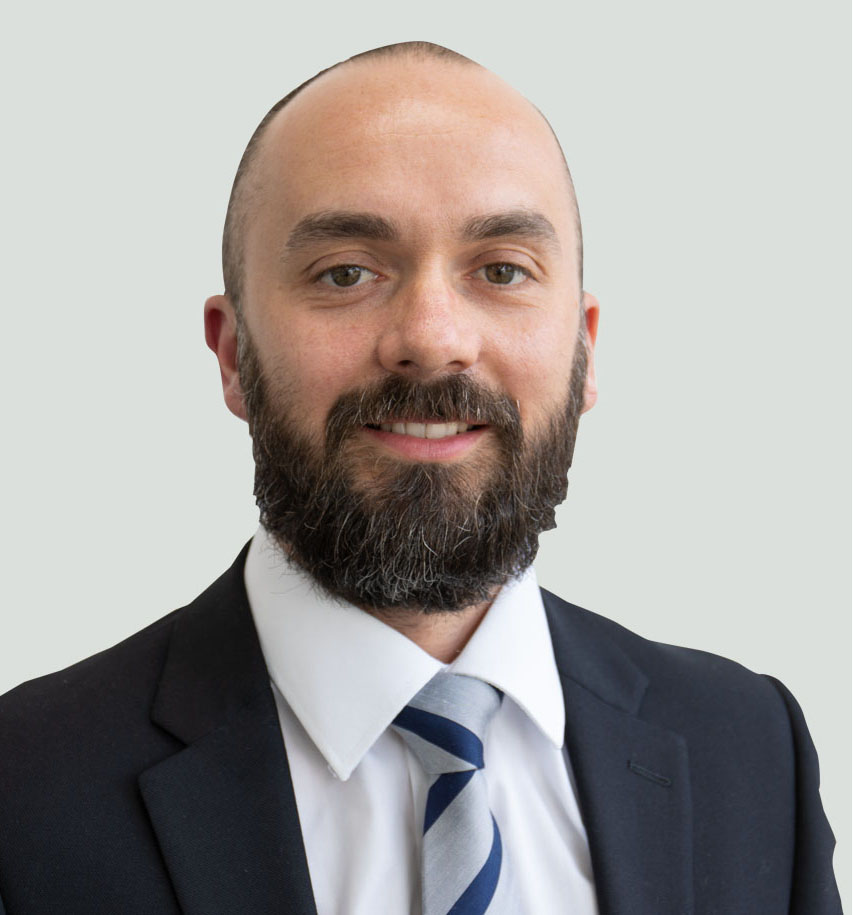
Jonathan Smith
Mortgage Consultant
Darren Rickard
Mortgage Consultant
Omer Mehmet
Managing Director
Contact Form
Our Equity Release Mortgages
Ready to explore your options? Contact Trinity Finance today
Book an appointment with our equity release mortgage specialist 01322 907 000
FAQs
What is equity release and how does it work?
Equity release is a way for homeowners aged 55 or over to unlock some of the value (equity) tied up in their home, without having to sell or move out. The most common type is a lifetime mortgage, which allows you to borrow a lump sum or smaller, flexible amounts against your property. Interest is charged, and the total amount owed is usually repaid when you die or move into long-term care.
Another option is a home reversion plan, where you sell a portion (or all) of your home to a reversion company in exchange for a lump sum or regular income, while retaining the right to live there rent-free for life. Both options are regulated by the Financial Conduct Authority (FCA) and come with consumer protections through the Equity Release Council.
Who is eligible for equity release?
Most equity release plans are available to UK homeowners aged 55 or over with a property typically worth at least £70,000. The home must be your main residence, and it should be in good condition and of standard construction. The amount you can release depends on your age, property value, and in some cases, your health and lifestyle. The older you are (or the shorter your life expectancy), the more you can usually release. Joint applications are based on the age of the youngest homeowner.
How much money can I release from my home?
The exact amount varies between lenders, but it usually ranges from 20% to 60% of your property’s market value. For example, a 55-year-old might be able to release around 25–30%, whereas a 75-year-old could potentially release 45–55%. Some providers offer enhanced plans for people with certain medical conditions or lifestyle factors, allowing them to release more money because their expected lifespan is shorter. Trinity Finance can provide a free, no-obligation quote showing how much tax-free cash you could access.
What can I use the money for?
You can use the money from equity release however you wish. Popular reasons include:
- Paying off an existing mortgage or loans
- Making home improvements
- Supplementing retirement income
- Helping children or grandchildren (e.g., house deposits or tuition)
- Funding travel or big life experiences
- Covering healthcare or long-term care costs
Because the money you release is classed as a loan, not income, it’s tax-free. However, taking a large lump sum may affect means-tested benefits, so it’s best to speak with an adviser first.
Will I still own my home?
If you take out a lifetime mortgage, you remain the legal owner of your home. The lender places a charge against it, just like a traditional mortgage. With a home reversion plan, you sell part or all of your home to the provider, meaning you no longer fully own that share — but you still retain the legal right to live in the property for life (or until you move into long-term care).
Do I have to make monthly repayments?
Most lifetime mortgages do not require you to make any monthly repayments — the interest simply “rolls up” (compounds) over time. However, many modern products now allow voluntary or partial repayments to help control the total interest. Some plans even allow you to pay the full interest monthly, meaning the balance doesn’t increase. At Trinity Finance, we’ll explore both roll-up and repayment options to find the most suitable plan for your goals.
What happens when I die or move into long-term care?
When the last homeowner on the plan dies or permanently moves into long-term care, the property is sold, and the proceeds are used to repay the loan plus any interest accrued. Any remaining funds then go to your estate or beneficiaries. Plans that comply with Equity Release Council standards include a no-negative-equity guarantee — meaning you or your estate will never owe more than the property’s final sale value, even if the market falls.
How does interest work on a lifetime mortgage?
Interest is either fixed or variable, depending on the plan. With roll-up interest, the unpaid interest compounds over time — you pay interest on both the loan and previously added interest. For example, a £50,000 loan at 6% interest would roughly double in around 12 years if no repayments are made. Alternatively, some plans offer interest-payment options allowing you to pay monthly interest to keep the balance steady. The right choice depends on your income, goals, and estate planning priorities.
Will equity release affect my family’s inheritance?
Yes — equity release will reduce the value of your estate because the loan and accrued interest (or reversion share) are repaid from your property when it’s sold. However, some products include inheritance protection options that guarantee a percentage of your home’s value will be passed on. If leaving an inheritance is important to you, we can find plans that balance cash access with legacy protection.
Can I move house after taking out equity release?
Yes — all plans approved by the Equity Release Council are portable, meaning you can move to another property that meets the lender’s criteria. If your new property is worth less, you might have to repay part of the loan, but you won’t lose the ability to move. Trinity Finance will guide you through this if you plan to downsize later.
What are the main costs involved in equity release?
Typical costs include:
- Adviser fee – usually £500–£1,000, sometimes fixed or percentage-based
- Lender’s arrangement fee – often around £300–£600 (some waive it)
- Valuation fee – usually £200–£500, though many plans include free valuation
- Solicitor’s fee – around £400–£800 for independent legal advice
Interest is then charged on the amount released. At Trinity Finance, we provide a full, transparent cost breakdown before you commit.
What protections do I have?
All legitimate equity release products must be regulated by the Financial Conduct Authority (FCA), and most advisers and providers belong to the Equity Release Council (ERC). ERC membership ensures:
- You retain the right to live in your home for life
- You have the right to move to another property
- A no-negative-equity guarantee protects your estate
- You must receive clear, fair, and transparent advice before proceeding
Will equity release affect my benefits or tax position?
The money you release is tax-free, but it could impact any means-tested state benefits such as Pension Credit, Universal Credit, or Council Tax Reduction, because it increases your savings or capital. It doesn’t affect your personal tax rate or income tax liability, but careful planning is important if you rely on benefits. Trinity Finance will assess this before recommending any product.
Can I pay off my equity release early?
Yes — you can repay it early, but there may be an early repayment charge (ERC) depending on the lender and the product type. Some plans have fixed ERCs, while others reduce over time. Many modern products now include flexible features such as downsizing protection, allowing you to repay early without penalty if you sell and move to a smaller home after a certain period (often 5 years).
How long does the process take?
The process usually takes 6 to 8 weeks, depending on your circumstances and the lender. The key stages are:
- Initial consultation and affordability checks
- Property valuation
- Offer issued by the lender
- Legal advice and signing documents
- Completion and release of funds
Trinity Finance will manage the entire process and liaise with solicitors and lenders to ensure it runs smoothly.
What if my property value goes up after equity release?
If your property increases in value, the lender does not gain from that rise — it’s still your property. However, if you’ve taken a home reversion plan, the provider only benefits from their purchased share. Rising property prices may also mean you can release more funds later through a further advance or additional drawdown, depending on your lender’s criteria.
What happens if I go into long-term care?
If you move permanently into long-term residential care, your home is usually sold and the equity release plan is repaid from the proceeds. If you are on a joint plan, this only occurs when both owners have moved into care. Until then, your partner or spouse can continue living in the home.
Is equity release safe?
Yes — equity release is now one of the most tightly regulated financial products in the UK. The FCA ensures all providers and advisers meet strict standards. In addition, the Equity Release Council guarantees consumer protection with clear rights such as lifelong home occupation and no-negative-equity safeguards. Working with a qualified, FCA-regulated adviser like Trinity Finance ensures you understand every risk and benefit before proceeding.
Can I take the money in stages rather than all at once?
Yes — many lifetime mortgages offer a drawdown facility that allows you to release smaller amounts over time, rather than one lump sum. This option helps control how much interest builds up, because you only pay interest on the money you’ve actually drawn. It also keeps your funds flexible for future needs such as care, travel, or family support.
Is equity release right for me?
Equity release can be an excellent option for homeowners who are property-rich but cash-poor and want to enjoy financial freedom in later life. However, it’s not suitable for everyone. If you wish to leave a large inheritance, plan to move soon, or have alternative income sources, other solutions (like downsizing or a retirement-interest-only mortgage) might be better. The best approach is to seek personalised advice. Trinity Finance provides a free, no-obligation review to help you compare all your options before deciding.
Equity Release Topics
Are you considering equity release?
Can you benefit from equity release with a bad credit rating?
Using equity release to reduce inheritance tax
Can you buy a second property using equity release?
Is equity release a good way to pay off your mortgage?
How does a retirement interest-only mortgage compare with equity release?
Equity Release Mortgage Lenders
Partner with specialist lenders who understand equity release